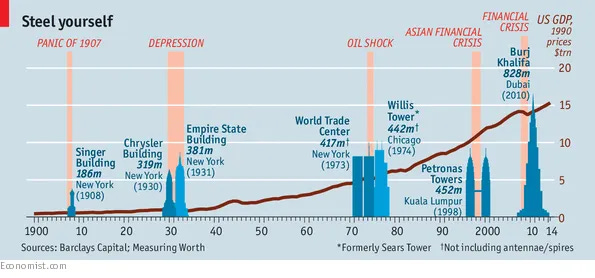
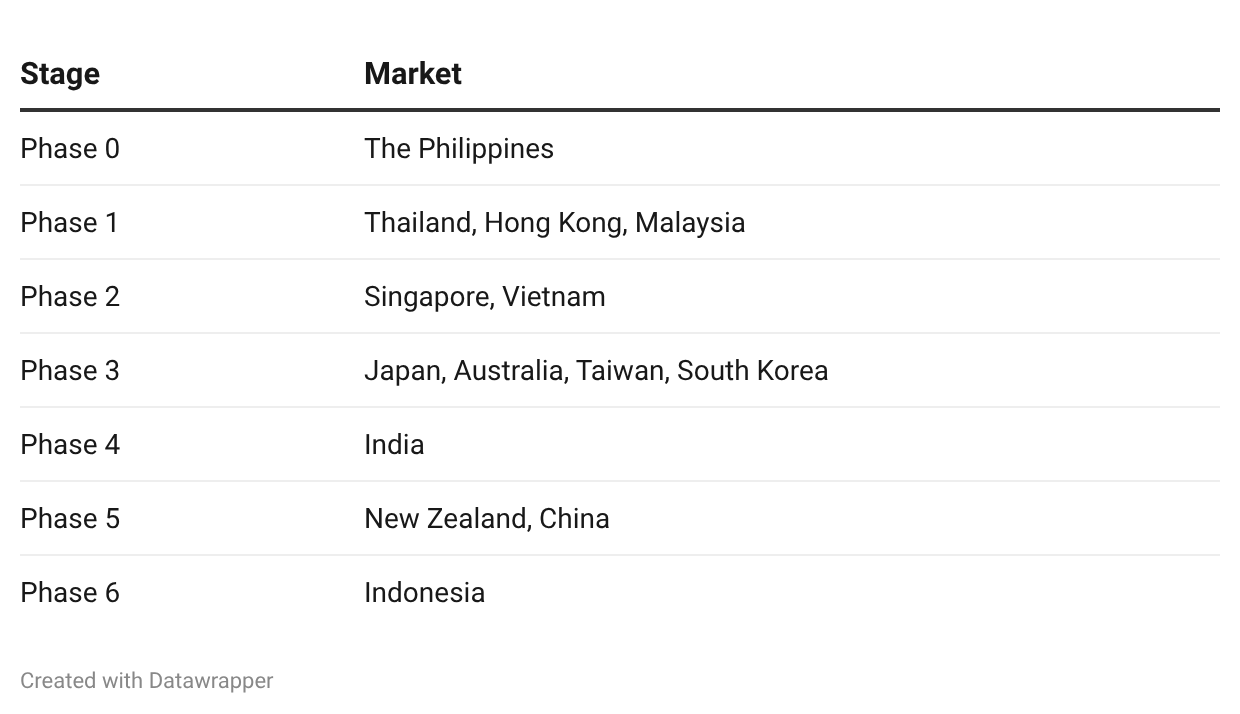
Faber argued that a typical emerging market tends to go through seven phases: zero being the bottom of the cycle and three its peak:
Fritzell then applied Faber’s template to 2026 Asian markets:
Unless Fritzell is talking about stock markets (which DON’T represent the real underlying economy e.g. look at the US stock market vs. underlying economy), I am not so sure about his placing of Malaysia in Phase 1 (while on my last long stopover in Taipei since COVID, I noticed construction had definitely perked up there no doubt thanks to the AI boom).
A short walk from me is the 106-story The Exchange 106 (the TRX area is a 70-acre integrated development with a massive mall that’s also supposed to be a global financial services center hub with dozens of highrises) that was completed a few years ago and I watched the 118-story Merdeka 118 (the second-tallest building and structure in the world after the Burj Khalifa) being built from my balcony (I don’t believe the mall under it is open yet). Malayan Banking Bhd (KLSE: MAYBANK / OTCMKTS: MLYBY / MLYNF) aka Maybank moved into it after leaving their 50 story tower nearby I assume mostly empty.
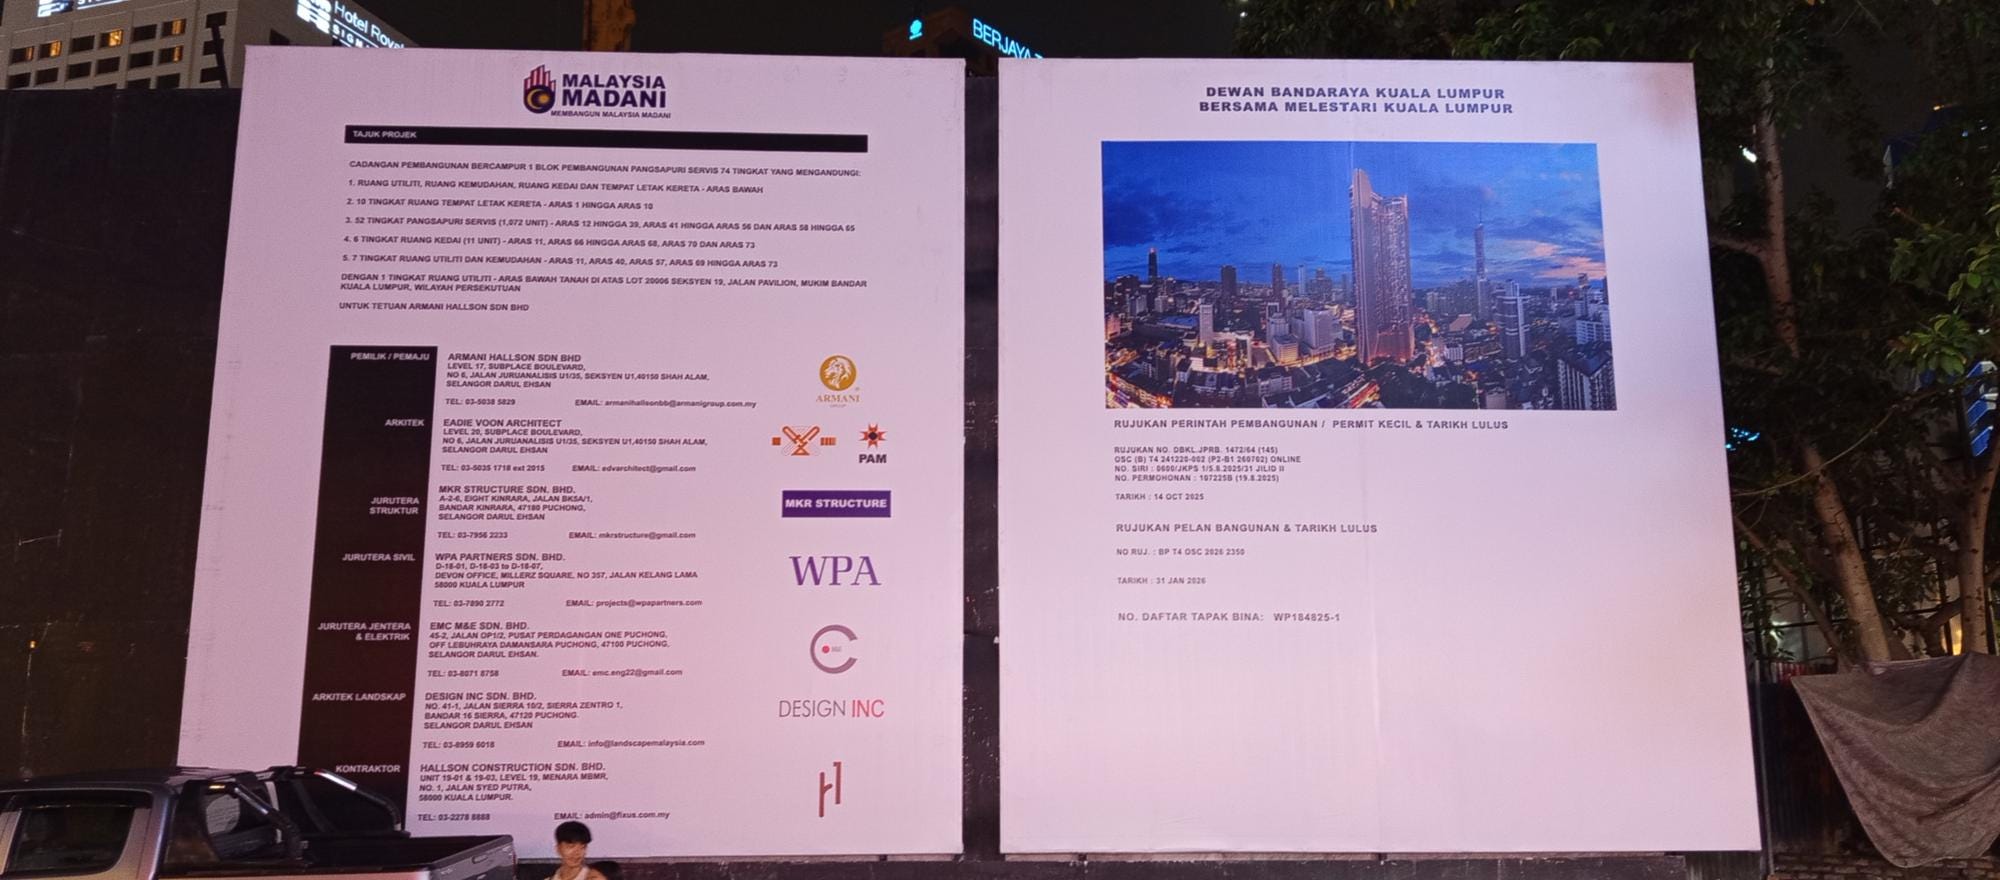
When I got back to KL last week, I walked by the parking lot at the foot of Jalan Alor (the overpriced outdoor eating street nearby) for it to be fenced off with a new sign for a 75 story tower that will contain over 1,000 serviced apartment units:
Its across the street from a much smaller high-rise project that’s been abandoned for some years (they just left the crane up) and about a block from the 79-story etc Plaza Rakyat complex project which has been abandoned and mired in lawsuits (and no doubt mosquitoes as the uncompleted basements get flooded) since the Asian Financial Crisis:
And across the street from the Petronas Towers where a Trump Hotel was supposed to go up before Covid, work is underway on what I presume will be a similar hotel or serviced apartment complex plus a new mall has opened by the towers / KLCC Park with long standing plans to eventually include a 145 story tower.
I am not going to bring up Forest City in JB as you can watch plenty of YouTube videos about the alleged state of that megaproject – although better connectivity to Singapore thanks to new infrastructure should help make it less of a “ghost city…”
Maybe with the situation in the Middle East, there could could be a business/expat shift to safer locales in SE Asia with Malaysia well positioned for Islamic banking, data centers and being an overall nice place to live OR the country could be poised to enter one of Faber’s later cycles (Phase 4 – downcycle doubts…)
$ = behind a paywall
$ = Behind a paywall / 🗃️ = Link to an archived article (Note: Seeking Alpha earnings/conference etc. presentations are typically not paywalled) / ⛔ = Article archiving may not be working properly
6,661 Japanese gas stations already sell KeePer coatings under licence. Now the best of them are converting into franchises. It trades at less than 10 times this year’s operating profit.
A KeePer coating is a thin glass film that goes onto car paint. The cheapest one, Crystal KeePer, takes a couple of hours and costs ¥18,200, about $117, on a small car. The most expensive, W Diamond KeePer, takes most of a day and costs ¥108,000, about $690, on a large one. What the customer is buying is a brand they recognise and trust, and a system that produces the same result in every shop allowed to use the name.
The shares trade at ¥3,650, which values KeePer Technical Laboratory Co Ltd (TSE: 6036), KeePer技研) at ¥99.6bn, or about $638m at ¥156 to the dollar. Revenue in the twelve months to June 2026 was ¥25.96bn, up 12.4%.
Shanghai focuses on family offices in effort to form global asset management hub by 2030
Asia has become the engine of wealth creation; and Shanghai, as a key financial centre in the region, is quietly catching up with other wealth hubs like Hong Kong and Singapore, and competing to provide better support for the development of the wealth management industry. In a new policy package, the Shanghai government has granted the family office official recognition.
In its new efforts to deepen the construction of a global asset management hub, the government has rolled out a series of guidance and opinions of 21 different initiatives, aiming to form a hub with a targeted total of 55 trillion yuan ( US$8.2 trillion ) of assets under management by 2030.
For the first time, official language places family offices alongside family trusts, buy-side investment advisory and cross-border asset allocation as standard instruments of modern wealth management.
In June 2026, not a single private equity (PE) or venture capital (VC) fund manager successfully registered with the Asset Management Association of China (AMAC) — the first month with no approvals since the registration system launched 12 years ago.
The freeze came as Chinese regulators tightened rules, culminating in the June release of Document No. 54, a directive issued by the State Council, China’s cabinet, to rein in a sprawling and sometimes unruly private fund industry.
The directive’s goal is to weed out weak, speculative, or fraudulent players by raising the barrier to entry. But in doing so, regulators have caused a fundamental reset of China’s primary market, accelerating a paradigm shift where independent venture capitalists are being squeezed out, state-backed entities are consolidating power, and policy-driven capital is generating highly concentrated tech bubbles.
The yuan’s steady climb toward a four-year high is drawing more foreign money into Chinese assets and strengthening Beijing’s push to expand the currency’s global use.
The onshore yuan opened stronger than 6.70 against the dollar Thursday for the first time in four years, after briefly touching 6.69 in the previous session. It closed at 6.7062, despite a weaker-than-expected fixing by the People’s Bank of China.
Alibaba (NYSE: BABA) reported mixed financial results, with strong cloud and artificial intelligence growth offset by profitability pressure from heavy investment.
Total revenue reached RMB 269 billion, up 9% year-over-year, driven largely by a 45% increase in Alibaba Cloud external revenue, marking the 22nd quarter of acceleration.
AI-related cloud products sustained triple-digit growth for the 12th consecutive quarter and reached an annualized revenue run rate of RMB 49.5 billion, or approximately USD 7.3 billion.
The video platform is planning a $700 million capital restructuring that turns Tencent (HKG: 0700 / LON: 0LEA / FRA: NNND / SGX: HTCD / OTCMKTS: TCEHY) from a core shareholder into a creditor through an equity-to-debt deal
Bilibili (NASDAQ: BILI)’s move would pretty much cancel out Tencent’s 9.6% equity stake, but the tech giant would get $200 million of convertible notes
Paired with a share placement and buyback, the transaction aims to cushion Bilibili’s share price and limit dilution, but growth remains a concern
JD.com(NASDAQ: JD / SGX: HJDD)’s second quarter of 2026 results showed a steady operational performance amid challenging macroeconomic and industry conditions, delivering a mix of positives and areas for cautious observation.
Revenues declined slightly by 2.9% year-over-year to RMB 346 billion, primarily due to headwinds in the electronics and home appliances categories.
This segment faced pressure from a high comparison base linked to last year’s trade-in program and upstream raw material cost increases.
JD.com(NASDAQ: JD / SGX: HJDD) unveiled an artificial intelligence strategy focused on robotics and hardware integration, anchored by plans to build a large computing cluster with domestic chipmaker Moore Threads Technology Co Ltd (SHA: 688795).
The move toward so-called physical AI sets the e-commerce company apart from domestic rivals Alibaba (NYSE: BABA) and Tencent (HKG: 0700 / LON: 0LEA / FRA: NNND / SGX: HTCD / OTCMKTS: TCEHY), as JD.com looks to capitalize on its extensive logistics network while contending with its first quarterly revenue decline amid weak consumer spending.
PDD Holdings (NASDAQ: PDD) orPinduoduo reported steady revenue growth in the second quarter of 2026 amid ongoing investments in platform governance, supply chain enhancement, and broader ecosystem support.
Group revenue rose 8% year-over-year to RMB 112.4 billion, driven primarily by an increase in transaction service revenues, which grew 13%.
However, net income declined 12% year-over-year to RMB 27.2 billion, influenced by elevated investment levels in platform improvement and industry ecosystem development.
NetEase(NASDAQ: NTES) reported steady financial and operational performance for the second quarter of 2026, with total net revenue reaching RMB 30.1 billion (USD 4.4 billion), driven predominantly by its games business.
The company’s games and related value-added services (VAS) generated RMB 25 billion in net revenues, reflecting a 10% year-over-year increase, despite a 2% sequential decline attributed primarily to certain self-developed and licensed titles.
This growth was supported by a diverse portfolio spanning original IPs, live operations, and innovations such as the recent launch of Sea of Remnants in China and new content updates to established games like Sword of Justice, Identity V, and the NARAKA: BLADEPOINT franchise.
China has temporarily suspended construction of new power and energy-storage battery projects pending a year-end review of industry capacity, as authorities intensify efforts to rein in severe overcapacity.
The move is the government’s latest intervention in a sector where planned new capacity this year has already climbed to about 1.5 times China’s total battery output in 2025.
China’s heavy truck market is on track to electrify far faster than previously expected, with new-energy models potentially accounting for half of sales by 2028, said battery giant Contemporary Amperex Technology Co. Ltd. (CATL) (SHE: 300750 / HKG: 3750 / SGX: HCCD / OTCMKTS: CYATY / CTATF)’s chief scientist.
The prediction underscores rapid acceleration in the electrification of the commercial road transport sector, driven by technological breakthroughs, continued government subsidies and high fossil fuel prices.
Retail sales of passenger cars in China plummeted 23.6% year-on-year in August, marking the second-sharpest monthly decline this year as the market showed no signs of a sustained recovery.
The monthly contraction brought total domestic retail sales of passenger vehicles for the first eight months of 2026 to 11.7 million units, a 20.8% drop from the same period last year, according to data released on Tuesday by the China Passenger Car Association (CPCA).
Chinese regulators recently issued a stern warning to the country’s automakers: Stop the cutthroat competition overseas. The guidelines, released jointly by the Ministry of Commerce and other top agencies, aim to police how Chinese auto companies price, market and manage their foreign operations.
The goal is to prevent a race to the bottom in global markets. Chinese automakers quickly fell in line, issuing pledges to comply. But curing this spillover of excessive competition requires a look at the disease itself. The root cause lies firmly within China’s borders.
Chinese auto parts manufacturers are stepping up cross-border e-commerce to capture a slice of the global automotive aftermarket, where online sales are growing rapidly.
The value of the global automotive aftermarket was $674.6 billion in 2024 and is expected to reach $804.8 billion by 2030, representing a compound annual growth rate of about 3%, said a representative from Amazon Global Selling at a company event held on Thursday in Ruian, eastern China’s Zhejiang province.
Lululemon Athletica Inc. shares plunged nearly 20% after the apparel maker reported declining second-quarter revenue and profit, dragged down by an abrupt sales reversal in China and persistent weakness across North America.
The stumble on the Chinese mainland — previously Lululemon’s primary growth engine — underscores how quickly localized marketing missteps and rising competition from rivals like Alo Yoga can derail multinational brands in critical consumer markets.
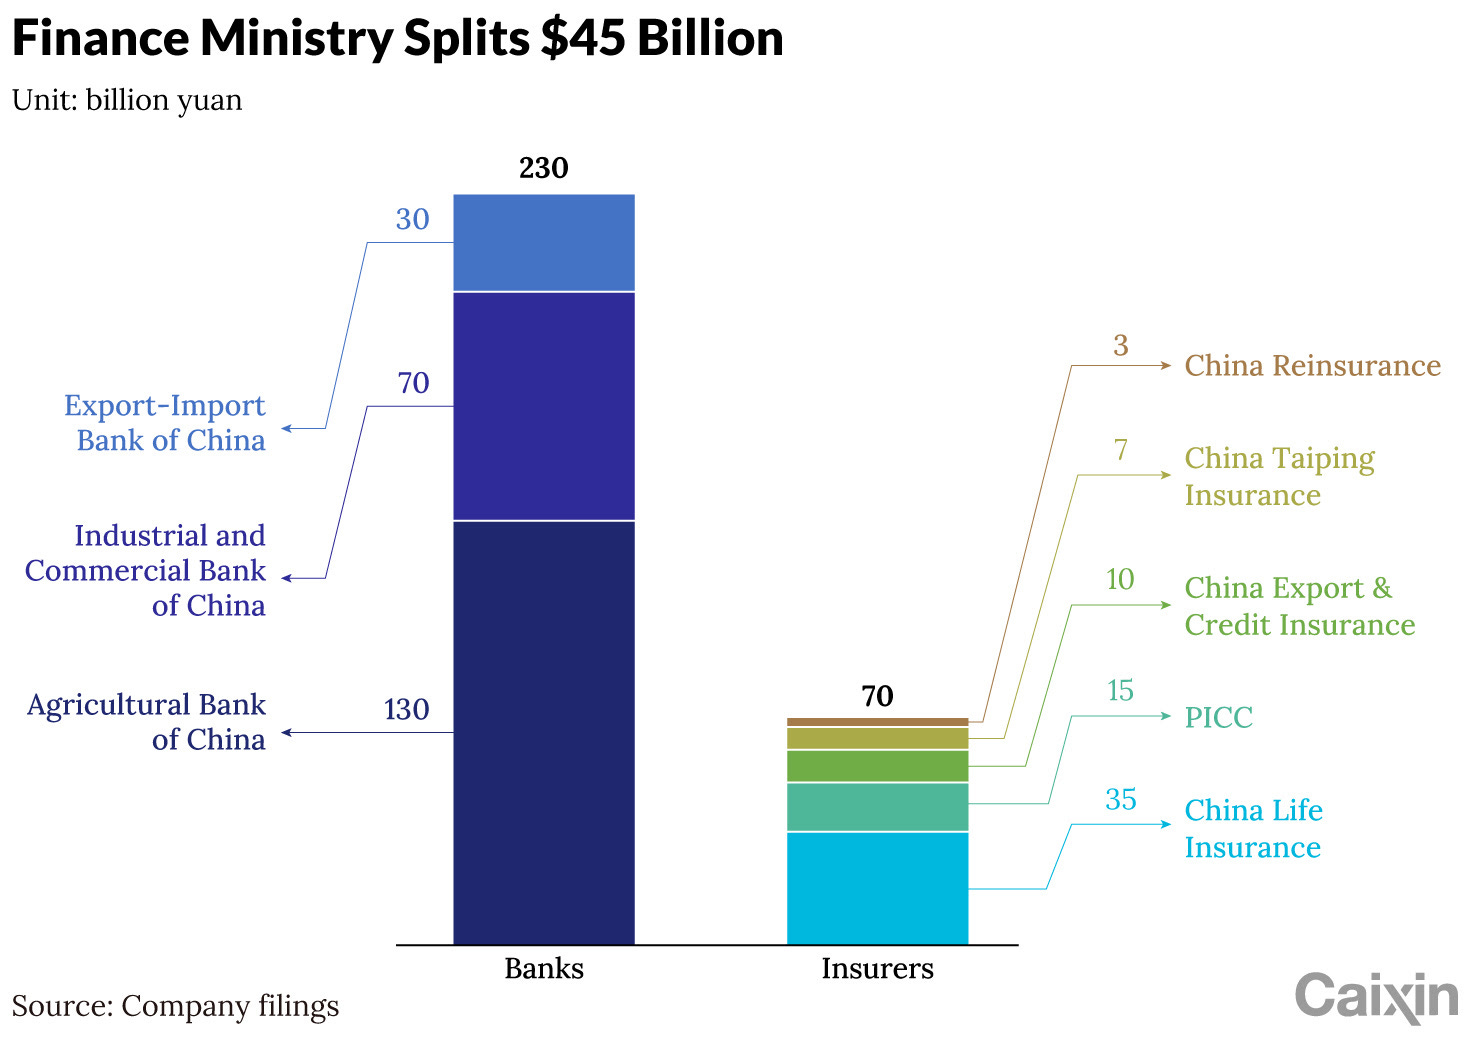
China is injecting 300 billion yuan ($44.7 billion) into three state-owned banks and five major insurers, broadening a government recapitalization drive as policymakers seek to strengthen financial institutions against mounting economic and market risks.
Of the total, 230 billion yuan will go to banks and 70 billion yuan to insurers, according to announcements Sunday from the institutions. The funding will come from special treasury bonds issued by the Ministry of Finance. The move also marks the first time Beijing has used the fiscal tool to recapitalize insurance companies.
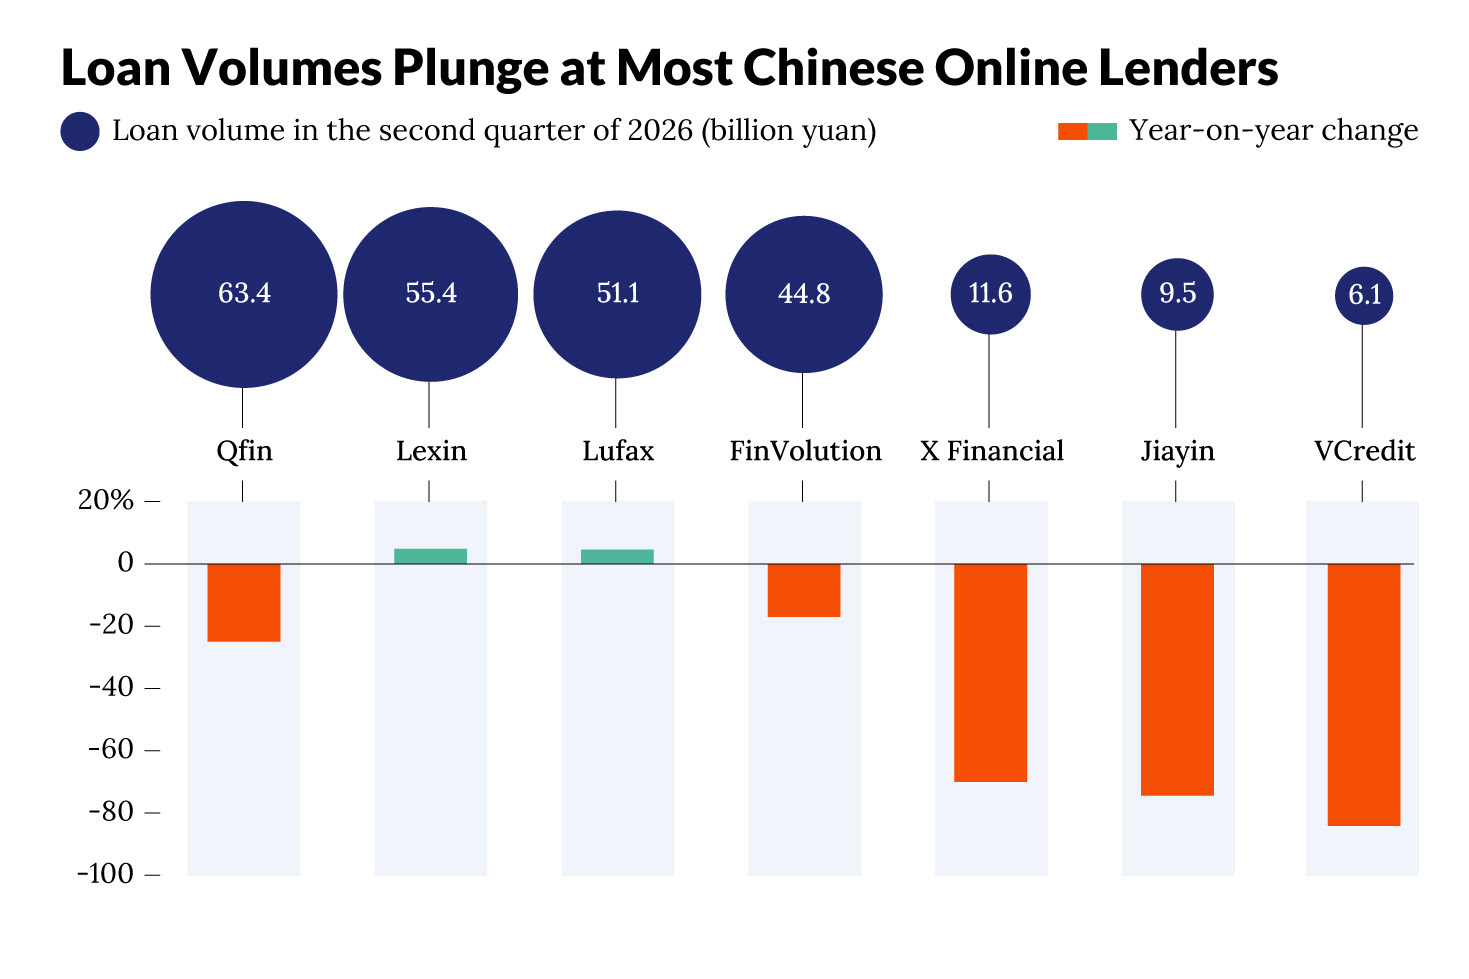
China’s online consumer lending platforms are taking a sharp hit from tighter rules on high-cost loans, with loan volumes shrinking, profits plunging and some companies falling into the red.
Six listed loan facilitation platforms had reported first-half 2026 results as of Monday, including Qifu Technology(NASDAQ: QFIN), FinVolution (NYSE: FINV), LexinFintech Holdings Ltd (NASDAQ: LX), X Financial (NYSE: XYF), Jiayin Group Inc (NASDAQ: JFIN) and Vcredit Holdings Ltd (HKG: 2003 / FRA: 5R6). Across the group, loan originations and outstanding balances fell sharply after new regulations capped total borrowing costs and tightened cooperation between banks and third-party lending platforms.
The rules are reshaping a business model that had relied heavily on higher-yield consumer loans.
The property developer received regulatory approval this month to issue a commercial real estate investment trust, or REIT
Seazen Group Ltd (HKG: 1030 / FRA: 6FLA / OTCMKTS: SZENF) plans to raise funds through a real estate investment trust whose main assets will comprise two of its shopping malls
The plan, which has been approved by the Chinese securities regulator, is expected to raise 1.5 billion yuan in much-needed funds
The solar panel maker will drop the “solar” from its English name, as it builds up a second business pillar investing in frontier industries
JinkoSolar Holding Co Ltd (NYSE: JKS) is adding a second business pillar by investing in emerging high-tech industries like AI, complementing its struggling legacy solar business
The company’s pivot includes early investments of typically 100 million yuan or less in AI startups Moonshot, StepFun and SiliconFlow
On the 20th January 2026, Skyworth Group Ltd (HKG: 0751 / FRA: KYW0 / KYW / OTCMKTS: SWDHY / SWDHF) announced an inter-conditional Scheme and concurrent listing of 70%-held Skyworth Photovoltaic (Skyworth PV) on the HKEx, by way of introduction.
Currently trading right at the Scheme cash consideration, assigning zero value for Skyworth PV. Skyworth’s share price is 22% below the pre-spin-off announcement price. I can see this trending lower.
Now contractor KFM Kingdom Holdings Ltd (HKG: 3816) is suspended pursuant to the Hong Kong Code on Takeovers and Mergers. Its share price is up ~700% since January.
Controlling shareholders exiting given protracted headwinds for Hong Kong’s private residential and commercial property markets makes sense. Less clear are these irrational price movements before a deal is struck.
SINGAPORE — For decades, Macao’s economic proposition was exceptionally simple: casinos, tourists and proximity to the Chinese mainland.
Sam Hou Fai, the chief executive of Macao SAR, is trying to make it considerably more complicated.
In an exclusive interview with Caixin Global during his first official visit to Southeast Asia since taking office, Sam laid out plans to build a more diversified economy around technology, finance, healthcare, education and culture — while using neighboring Hengqin island to overcome one of Macao’s most basic constraints: its tiny physical footprint.
Macau’s casino gross gaming revenue (GGR) tracked seasonal softness in the first six days of September, averaging MOP633 million (US$78.34 million) per day, suggested banking institution UBS in a memo, citing its own channel checks.
The average daily GGR run-rate for the September 1 to 6 period was up circa 4 percent year-on-year; though it was down about 11.5 percent when compared to the average daily GGR of MOP706 million in August, noted UBS.
Macau’s number of visitor arrivals reached 30 million as of 11am on Friday (September 11), a milestone achieved 22 days earlier than in 2025, according to a Friday update from the city’s Public Security Police.
The police – responsible for handling the city’s immigration checkpoints – said the city’s visitor volume has shown “stable growth”, benefiting from the Chinese central government’s visa policies and the “summer peak” travel season.
Macau’s gaming sector saw its spending under the combined category of “purchase of goods, commissions and customer rebate” rise 11.6 percent year-on-year in 2025, to MOP25.88 billion (US$3.20 billion), according to the city’s Statistics and Census Service.
Such spending represented approximately 25.5 percent of the gaming sector’s total expenditure for 2025, according to GGRAsia’s calculations based on official data. Total expenditure – excluding taxes – increased by 7.5 percent year-on-year, to MOP101.44 billion, showed the latest annual “Gaming Sector Survey” published on Friday.
Mainland China-based hotel operator MGM Hospitality Group (Asia Pacific) Ltd is to strengthen collaboration with its parent, MGM China Holdings Ltd (HKG: 2282 / FRA: M04 / OTCMKTS: MCHVF / MCHVY), to bring “new cultural tourism” experiences to Macau and the wider Guangdong-Hong Kong-Macau Greater Bay Area, as well as expand the region’s international visitor base.
Casino operator Wynn Resorts Ltd (NASDAQ: WYNN) says its financing arm is proposing a US$900-million private offering of 6.875-percent senior notes due in 2035.
The notes are being issued by Wynn Resorts Finance LLC and its subsidiary Wynn Resorts Capital Corp, both indirect wholly-owned units of Wynn Resorts, according to a Thursday announcement.
The offering is expected to close on or about September 22, “subject to customary closing conditions,” the firm stated.
On 10 September, Mirae Asset’s Global X Japan launched Japan’s first exchange-traded fund called Global X Korea Semiconductor TOP10 ETF focusing directly on South Korean semiconductor companies.
This ETF tracks the yen-denominated index of the ‘FnGuide Semiconductor TOP10 Index,’ which comprises ten South Korean semiconductor firms.
Given strong demand for Samsung Electronics (KRX: 005930 / 005935 / LON: BC94 / FRA: SSUN / OTCMKTS: SSNLF) and SK Hynix (KRX: 000660) along with the need to enhance diversification, this Global X Korea Semiconductor TOP10 ETF could gain much higher demand in Japan.
KODEX AI Electric Power Core Facilities ETF (487240 KS) had a market cap of 3.2 trillion won as of 11 September 2026, up 104% in the past one year.
In this insight, I discuss the impact of rebalance of the iSelect AI Power Core Equipment Index in December 2026 which impacts the KODEX AI Electric Power Core Facilities ETF.
Mirae Asset TIGER Semiconductor TOP 10 ETF’s AUM has now surpassed 10 trillion won, up more than 200% since the beginning of the year.
In this insight, I discuss the impact of this change on FnGuide Semiconductor Top10 Index Rebalance on ETFs such as Mirae Asset TIGER Semiconductor TOP10 ETF in October 2026.
HPSP (KOSDAQ: 403870) is a potential inclusion candidate in the FnGuide Top 10 Semiconductor index rebalance in October. Leeno [LEENO Industrial (KOSDAQ: 058470)] is a potential exclusion candidate.
South Korea’s proposed changes to casino regulations could be delayed “until later this year,” as the government continues consultations with gaming operators amid industry concerns about the measures.
The information was obtained by GGRAsia from multiple South Korean casino industry sources and also carried in a report published on Tuesday by local news outlet Money Today Network (MTN).
The country’s Ministry of Culture, Sports and Tourism is seeking to amend the Tourism Promotion Act to raise the maximum Tourism Promotion and Development Fund contribution rate for casino operators from 10 percent to 15 percent of annual gross gaming revenue (GGR), as well as to introduce a five-year licence-renewal system.
South Korea’s casino sector should continue to benefit from record inbound tourism, although the impact is likely to be stronger for mass-market gaming than for VIP play, said NH Investment & Securities.
Analyst Lee Hwa-jeong said in a recent memo that South Korea received 12.8 million inbound visitors in the first seven months of 2026, an all-time high for the period. The brokerage expects the country’s full-year inbound visitor tally to reach 23 million.
Growth has been driven primarily by an increase in Chinese tourists, while arrivals from Japan and Western markets have also expanded, according to the institution.
NFC Corp (KOSDAQ: 265740) is a Korean cosmetics company which has rapidly increased its ODM business sales in the past two years.
NFC’s customers include Equalberry, Cellimax, Dr. Althea and Beauty of Joseon, brands whose products are increasingly visible outside Korea.
Based on consensus net profit estimate of 18.5 billion won (2027E) and a 12x P/E, this would result in a market cap of 222 billion won (91% higher than now).
Two years have passed since the fight for the control of Korea Zinc (KRX: 010130) erupted. Despite having lower stake, Chairman Choi alliance has maintained control over the company.
It is estimated that MBK/Young Poong Precision Corporation (KOSDAQ: 036560) alliance has a combined stake of 42.1% stake in Korea Zinc versus 38.8% for the Chairman Choi alliance.
Fight for control of Korea Zinc is far from over. MBK/Young Poong alliance is likely to stage a third proxy battle for Korea Zinc against Chairman Choi in March 2027.
After the market close on 9 September, it was reported that Hong Ra-hee is selling a 0.11% stake in Samsung Electronics (KRX: 005930 / 005935 / LON: BC94 / FRA: SSUN / OTCMKTS: SSNLF) (worth 1.94 trillion won) to her son Lee Jae-yong.
Her decision to transfer the shares directly to Chairman Lee rather than selling them on the open market is seen as a move to minimize the impact on the market.
After this transaction is completed, Lee Jae-yong’s stake in Samsung Electronics will rise from 1.47% to 1.58%.
Infinitt Healthcare Co Ltd (KOSDAQ: 071200) announced a major dividend program of providing 65.4 billion won in dividends to shareholders from 3Q 2026 to 2Q 2027.
Given the company’s current market cap of 276 billion won, the dividend amount of 65.4 billion won represents 24% of its market cap.
The company has a strong balance sheet. Net cash was 212 billion won at the end of 2Q 2026, representing 79% of market cap.
Big Wave Robotics IPO is expected to start trading on 29 September. The company has lowered the IPO price range to 15,000 won to 18,000 won per share.
To satisfy market expectations and regulators, Bigwave Robotics lowered its target offering price band and reduced the total number of shares offered.
My updated valuation analysis suggests a target price of 27,575 won per share, which is 53% higher than the recently lowered high end of the IPO price range.
China’s F&B chains aren’t expanding into Malaysia by choice – their own consumers left them no other option.
Chinese F&B firms are fleeing brutal domestic price wars, with Beijing restaurant profits falling nearly 90% year-on-year in early 2024.
Malaysia attracts Chinese operators due to its Chinese-Malaysian consumer base, lower rents, and strong returns, with one chain recouping USD235,000 in nine months.
Local businesses face intense pricing pressure, but niche, distinctive operators are better positioned to survive than undifferentiated mid-market players.
Fitch Ratings on Monday downgraded the long-term issuer default rating of gaming and plantations conglomerate Genting Berhad(KLSE: GENTING / OTCMKTS: GEBHY) to ‘BBB-’, from ‘BBB’, with a ‘stable’ outlook, as the rating agency expects its pace of deleveraging to be “slow” due to “substantial” capital commitments to expand key gaming properties, including those in Singapore and New York.
“This downgrade reflects our expectation that Genting Bhd’s proportionately consolidated EBITDA [earnings before interest, taxation, depreciation, and amortisation] net leverage ratio will stay above 4.0 times for the next three years,” Fitch suggested.
It added: “This is compounded by a slower-than-expected EBITDA ramp-up at Genting New York LLC because of high start-up operating costs, as well as more gradual recovery across Genting Bhd’s other gaming operations.”
Global casino operator Genting Berhad(KLSE: GENTING / OTCMKTS: GEBHY) may see earnings from its Malaysia gaming and leisure operations remain “soft” for the rest of 2026, amid high airfares and macroeconomic uncertainty, suggested Fitch Ratings in a Monday rating action commentary.
The ratings agency expects the performance of Genting Malaysia’s domestic operations to improve by 2 percent for full-year 2026, as revenue continues to recover from a weak first quarter.
Nonetheless, Fitch stated: “We expect [Malaysian operations] earnings to stay soft for the rest of the year, as revenue from international tourists and domestic traffic may still face challenges due to high airfares and macroeconomic uncertainties.”
S&P Global Ratings says Malaysian gaming and plantations conglomerate Genting Berhad(KLSE: GENTING / OTCMKTS: GEBHY) has “no more buffer” for further earnings disappointment, with elevated spending and weak operating results keeping the group at risk of losing its investment-grade rating.
The ratings agency said in a Tuesday report that Genting’s ratio of funds from operations (FFO) to debt was likely to remain at about 15 percent to 17 percent through 2028, below the institution’s 20-percent downside trigger.
Genting and several of its subsidiaries are rated by S&P at “BBB-” – the lowest investment-grade level – with a “negative” outlook.
The Malaysian government’s decision to engage Alton Aviation Consultancy to assess AirAsia Group’s funding needs has sparked debate. Critics argue that AirAsia is a private company, not a government-linked corporation, and that using taxpayer funds to review its liquidity interferes in free-market outcomes.
This move also serves as an early indicator of underlying economic stress that headline performance figures may not yet fully capture. Much like the US government’s interventions to stabilise banks in 2008, before the full depth of the financial crisis was reflected in every official statistic. As a consequence, authorities sometimes act when key private institutions face acute liquidity pressures that could cascade through the wider system.
Psychologically, the fall of a company the size of AirAsia could trigger economic ripples that undermine confidence more broadly. In an economy already confronting multiple external threats that includes sharp rises in aviation fuel prices, the visible distress or collapse of a major national carrier potentially risks amplifying uncertainty among investors, travelers, suppliers and consumers.
PhilWeb Corp (PSE: WEB), a Philippine-listed business-to-business (B2B) services provider for the country’s online gaming sector, and its wholly-owned subsidiary PhilWeb Capital Corp have agreed to invest an aggregate of nearly PHP4.23 billion (US$67.6 million) in JKS Tech Solutions Inc, a gaming system administrator accredited by the nation’s casino regulator.
In a separate Monday filing, PhilWeb said JKS Tech had agreed to acquire approximately 81.38 million PhilWeb treasury shares at PHP16.50 each, for an aggregate of about PHP1.34 billion. The shares represent approximately 4.85 percent of PhilWeb’s issued and outstanding stock.
PhilWeb Corp (PSE: WEB), a Philippine-listed business-to-business (B2B) services provider to the country’s online gaming sector, says its investment in gaming system administrator JKS Tech Solutions Inc represents a “highly capital-efficient” transaction that could help accelerate PhilWeb’s development as an “artificial intelligence (AI)-enabled digital infrastructure and technology platform serving the regulated digital entertainment sector”.
That is according to an executive summary filed by PhilWeb with the Philippine Stock Exchange on Wednesday.
DigiPlus Interactive (PSE: PLUS), a provider of online gambling services in the Philippines and holder of licences in South Africa and Brazil, is likely to face a 20.3 percent decline in annual earnings before interest, taxation, depreciation, and amortisation (EBITDA) for 2026, to about PHP11.4 billion (US$181.8 million).
That is according to an estimate released on Thursday by Moody’s Ratings, as it assigned Philippine-listed DigiPlus a first-time B1 corporate family rating – below investment grade. The outlook is ‘stable’.
“DigiPlus’ concentration in the Philippines exposes the company to earnings volatility amid frequent regulatory changes,” said the credit rating agency.
With 20 brands in 33 countries, the Philippine fast-food operator has abandoned earlier plans to list its international operation in New York in favor of its nearby neighbor
Jollibee Foods (PSE: JFC / OTCMKTS: JBFCF / JBFCY) calls Hong Kong “a natural market” for listing its international operation, reversing its previous commitment to a U.S. IPO
The Hong Kong Stock Exchange’s recent reforms and access to Mainland Chinese investors helped to seal the deal
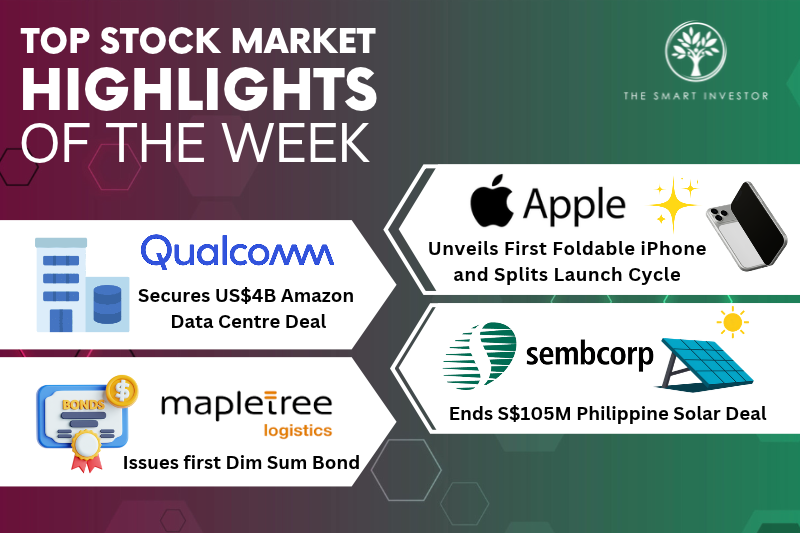
We look at Apple’s shift to a split iPhone launch strategy, a major AI chip partnership, and two corporate developments from Singapore-listed companies.
A foldable debut and split launch reshape Apple’s product cycle
A US$4 billion warrant deal underscores Qualcomm’s data centre push
Sembcorp walks away from a Philippine solar farm acquisition
Sembcorp Industries (SGX: U96 / FRA: SBOA / OTCMKTS: SCRPF) has terminated its S$105 million deal to acquire Philippine solar farm developer Puente Al Sol, citing prevailing market conditions and evolving strategic priorities.
The Singapore-based energy company had originally agreed to purchase Puente Al Sol from CleanCurrent Renewable Energy in January 2025.
Mapletree Logistics Trust taps the offshore renminbi market
Mapletree Logistics Trust (SGX: M44U / OTCMKTS: MAPGF), or MLT, has priced its inaugural dim sum bond – a 500 million yuan (US$74.5 million) offshore renminbi issuance bearing a coupon of 2.1% per annum.
Proceeds from the three-year bond will fund general corporate purposes, including refinancing existing borrowings.
Fitch Ratings assigned the bond a long-term rating of BBB+, in line with MLT’s issuer default rating.
Keppel REIT, MPACT, MLT and Keppel DC REIT are rewarding unitholders this week, but can their distributions remain sustainable?
Temasek, a global investment company headquartered in Singapore, holds 100% of Mapletree Investments and 21% of Keppel Ltd (SGX: BN4 / FRA: KEP / KEP1 /OTCMKTS: KPELY / KPELF) as of 31 March 2026.
A retirement portfolio is about more than a high dividend yield. These four Singapore stocks offer strong cash flow, sustainable dividends and businesses with room to grow.
What could S$100,000 invested across five Singapore dividend stocks generate each year? We break down the potential income while examining dividend yields, payout sustainability, and the growth prospects behind each stock.
SGX is a toll booth on the financial markets – whether equity prices rise or fall, the exchange collects a fee regardless, which underpins a resilient business model that generates consistent cash flow.
Capping our list is Singapore’s vehicle inspection and technical testing business – a dominant player with recurring, non-discretionary demand.
VICOM holds roughly S$53 million in cash and zero debt, providing a strong capacity for the company to reinvest in its business and to grow its dividends.
So, How Much Could S$100,000 Generate?
Could the S$100,000 Generate More Over Time?
What Could Reduce Your Dividend Income?
Get Smart: S$100,000 Is a Starting Point, Not the Finish Line
VICOM, the vehicle testing and inspection unit of ComfortDelGro Corporation (SGX: C52), raised its interim dividend by 27.4% to S$0.0395 per share.
Operational performance provided clear support for the increase.
Is CBA rewarding shareholders in more ways than one?
Credit Bureau Asia (CBA) – which provides credit scoring and risk analytics across Singapore, Malaysia, Cambodia, and Myanmar – declared an interim dividend of S$0.022 per share, up 10% from S$0.020 a year ago.
Does HRnet’s cash position support a bigger dividend?
Get Smart: The question behind every dividend hike
Three Singapore dividend stocks are rewarding shareholders with higher payouts this week, with free cash flow offering clues on future dividend sustainability.
The payout increases range from 33.3% to a generous 77.8%.
Can Hong Leong Asia sustain its 50% higher dividend?
Hong Leong Asia declared an interim dividend of S$0.03 per share, up 50% from S$0.02 a year ago.
Top-line expansion was anchored by its powertrain unit, Yuchai, which grew revenue by 16.8% as heavy-duty truck engine unit sales jumped 47.3% – substantially outperforming the 13.1% growth seen across China’s broader heavy-duty truck market.
Meanwhile, the Building Materials Unit expanded revenue by 24.1% on higher ready-mix and precast concrete volumes.
What’s behind First Resources’ 77.8% dividend increase?
First Resources led the pack in headline dividend growth, declaring an interim dividend of S$0.08 per share – a 77.8% jump from S$0.045 a year ago.
The integrated palm oil producer generated US$973.6 million in revenue for 1H2026, up 44.5% YoY.
Is Food Empire’s dividend increase backed by cash flow?
Food Empire declared an interim dividend of S$0.04 per share, up 33.3% from S$0.03 a year ago.
The instant beverage manufacturer reported US$315.1 million in 1H2026 revenue, a 15.0% YoY increase across all six operating regions.
As the JB-Singapore RTS Link nears completion, these three Singapore REITs could benefit from rising tourism, retail spending and cross-border traffic.
CICT could become one of the greatest beneficiaries, with its robust portfolio of premier retail assets such as Funan, Plaza Singapura, Raffles City, and Bugis Junction, at the heart of the city centre.
Notably, it’s not heavily dependent on them, unlike other pure-play retail REITs.
Starhill is another contender primed to snap up the increased discretionary spending as the central area becomes a destination for premium consumption.
And discretionary spending in this region is anchored by the shopping belt of Orchard Road.
Anchored by its flagship retail asset of Suntec City Mall, Suntec is another REIT poised to benefit from the central area as a magnet for increased international travel.
Crucially, Suntec City is more than a mall – it’s also a massive hub for MICE events.
Get Smart: The Central Region Taking Growth Centre Stage
Wilmar and First Resources give investors exposure to Southeast Asia’s palm oil industry, but their dividend profiles, earnings resilience and growth prospects differ. Which stock offers the better income opportunity?
iFAST Corporation Limited (SGX: AIY / FRA: 1O3 / OTCMKTS: IFSTF) is targeting 150% dividend growth in three years, with rising profits and revenue providing the financial support for higher payouts.
How fast is the platform growing?
What’s happening in Hong Kong?
How is the UK bank contributing?
Can iFAST keep raising its dividend?
Get Smart: The Revenue Engine Behind iFAST’s Rising Dividend
Genting Singapore (SGX: G13 / FRA: 36T / OTCMKTS: GIGNF / GIGNY) has attracted income investors with its sizeable dividend payouts, but improving earnings, cash generation and capital management could determine whether its dividend story is becoming more sustainable.
Why Genting Singapore’s Earnings Have Been Under Pressure
Genting Singapore owns and operates Resorts World Sentosa (RWS), which forms the main focus of its business. Other than RWS’s casino operations, the tourism landmark also offers hotels, attractions such as Universal Studios Singapore, and retail outlets.
The picture is a little different across Genting Singapore’s two main businesses.
Free Cash Flow Is the Bigger Dividend Question
Earnings Payout Ratio
Balance Sheet
Capital Requirements
What Could Make Genting Singapore a Better Dividend Stock?
What Could Threaten the Dividend?
Is Genting Singapore a Dividend Grower or a Dividend Payer?
How Does Genting Singapore Compare With Other Singapore Income Stocks?
Get Smart: A Better Dividend Stock Needs More Than a High Yield
RBI rejects group’s appeal against forced listing, setting the stage for what could become India’s biggest IPO
India’s central bank has rejected Tata Sons’ bid to avoid having to go public in a move that will force the vast conglomerate to undertake a radical transformation of its structure and operations.
Marksans Pharma Ltd (NSE: MARKSANS / BOM: 524404) posted its highest-ever quarterly EBITDA (INR 213 crore) and PAT (INR 159 crore) in Q1FY27, with UK and Europe overtaking as a genuine second growth engine.
Operating leverage, a bolt-on European buildout and a cash pile crossing INR 1,000 crore reshape the growth and capital allocation narrative heading into FY27.
Management’s conservative guidance hold, flagged margin normalization and looming capacity constraints deserve closer scrutiny than the headline beat suggests.
Fabrinet (NYSE: FN) reported strong financial results for the fourth quarter of fiscal year 2026, capping a year of accelerated growth with revenues reaching $1.316 billion, a 45% increase year-over-year, and surpassing the high end of its guidance.
Fiscal year 2026 revenue totaled $4.6 billion, up 36% from fiscal 2025, accompanied by a 39% rise in non-GAAP earnings per share to $14.09.
This growth was broadly based across multiple product lines and customers, particularly driven by increasing demand in the data center and communications infrastructure markets.
The company [Glass Wall Systems] has opened its INR 428 crore IPO (Price Band: INR 172–INR 182, closing Sept 10, 2026), backed by INR 128 crore raised from marquee anchor investors.
Proceeds from the INR 60 crore fresh issue will fully fund a new Glass Processing Unit (GPU) at the Vile Bhagad facility, bringing manufacturing processes in-house to reduce supply dependency.
Order book stands at more than 2x FY26 revenue (INR 981.54 crore total across domestic façade, international supply, and luxury fenestration as of July 2026).
Karamtara Engineering opens its Rs.875 crore IPO on September 9, 2026, with a price band of Rs.241 to Rs.254 per share, closing September 11.
The company is India’s largest integrated maker of solar mounting structures, growing revenue at a 33% CAGR over FY24 to FY26, though supplier and customer concentration are both rising.
At close to 32 times FY26 earnings at the top of the band, issue prices at premium to most listed peers, making capacity ramp-up and cost control the key monitorables.
Karamtara Engineering(KANOHAR IN), a Meerut based transformer and EPC company, opens its INR 1,055.74 crore IPO on September 8, 2026, priced at INR 601–632 a share.
The company has grown revenue 2.4x in two years on the back of a 500 MVA, 400kV order from Power Grid, but customer concentration and capacity utilisation remain watch points.
IPO looks aggressively priced as compared to other listed company in similar space.
Insight on SEBI’s new consultation paper on review of Certain Aspects of the Closing Auction Session(CAS) , Market Timings and Settlement Methodology for Derivatives Contracts.
We discuss the various aspects of the paper presented by SEBI.
Finally, we discuss how the impacts the NSE IPO which is opening this week.
Elbit Systems Ltd (NASDAQ: ESLT) reported solid financial performance in the second quarter of 2026, marked by double-digit growth in revenues, backlog, operating profit, and earnings per share.
Revenue increased by 15.9% year-over-year to $2.29 billion, with strong contributions from Europe (25%), North America (20%), Asia-Pacific (14%), and Israel (37%).
The diverse geographical revenue mix reflects demand across multiple regions, notably backed by inventory replenishment in Israel following regional conflicts.
🌐 Gold Fields (JSE: GFI / NYSE: GFI) – One of the world’s largest gold mining firms. 9 operating mines in Australia, Peru, South Africa & Ghana (including the Asanko JV) & 2 projects in Canada & Chile. 🇼🏷️
🌍 FirstRand (JSE: FSR / FRA: FSRA / OTCMKTS: FANDY / FANDF) – Portfolio of integrated financial services businesses, operates in South Africa, certain markets in sub-Saharan Africa, UK & India. 🇼🏷️
🇪🇺🏛️ CEZ as (PSE: CEZ / WSE: CEZ / FRA: CEZ / OTCMKTS: CZAVF) – Generation, distribution, trading & sale of electricity & heat; trading & sale of natural gas; provision of comprehensive energy services from the new energy sector & coal mining. One of the 10 largest energy companies in Europe. 🇼🏷️
Investors seeking shelter from geopolitical turmoil have put the outflows of recent years into reverse.
The net $3.6bn pumped into LatAm-focused mutual and exchange traded funds comes after investors withdrew a net $15.1bn from the funds over the previous 15 years, according to data from Morningstar.
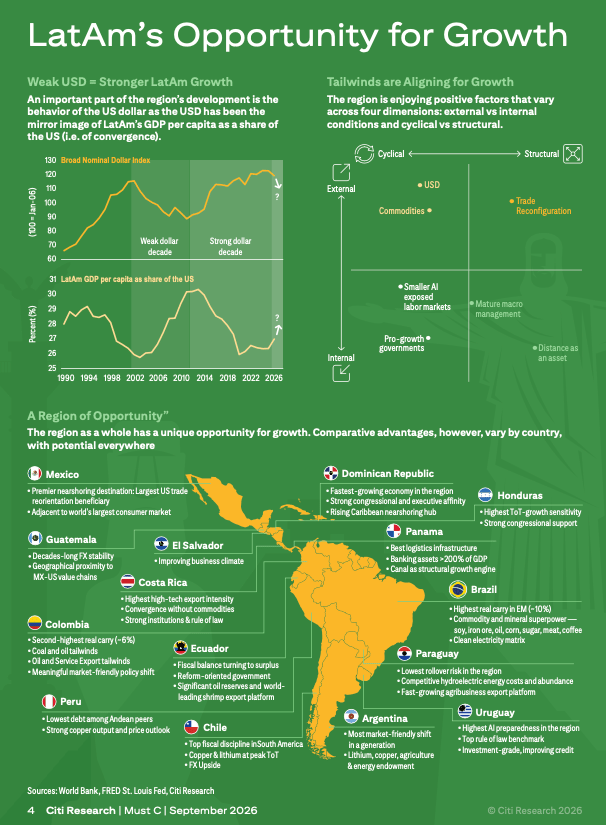
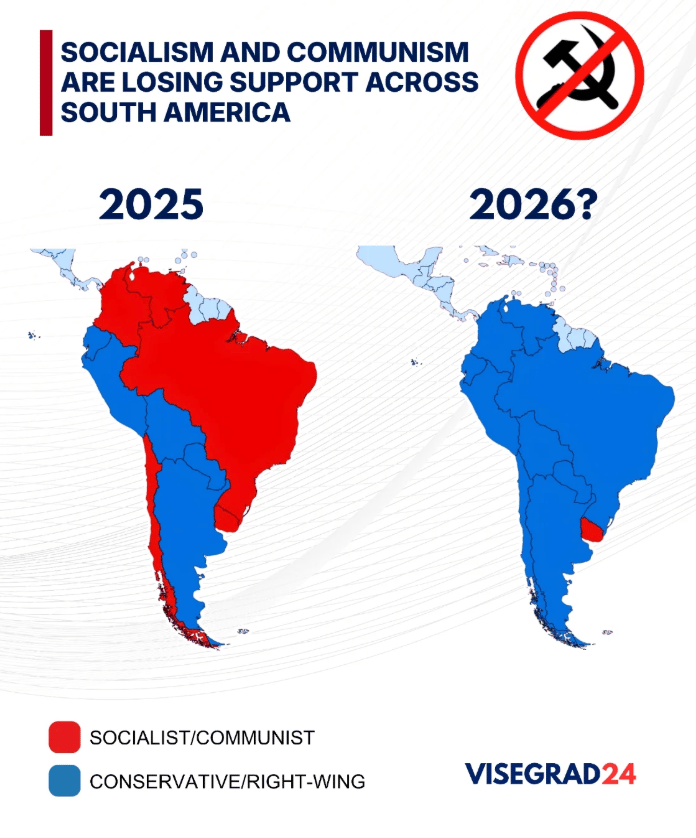
Our focus on South America’s improving investment outlook, underpinned by a generational shift from left-wing governments to more business-friendly governments, gained support Thursday from Citi’s report, “LatAm Poised for Take-Off: The Macro Cycle Turns Latin America’s Way.”
Citi chief Latin America economist Ernesto Revilla wrote in a note earlier today that a right-wing political shift is serving as a tailwind alongside a weaker dollar, firm commodity prices, and global supply-chain realignment, while stressing that lasting gains depend on reforms and execution.
Here is Revilla’s take on improving LatAM markets:
StoneCo Ltd (NASDAQ: STNE) reported steady progress in the second quarter of 2026, showing cautious optimism amid a complex operating environment marked by elevated interest rates and macroeconomic challenges.
Total payment volume (TPV) growth accelerated modestly to 4% year-over-year, reflecting early encouraging signs from retention initiatives, particularly among micro merchants where simplified offerings and improved client experience have helped reduce churn.
However, challenges remain with small and medium-sized businesses (SMBs), given their diverse needs and more complex sales channels, which require prolonged, calibrated efforts to achieve meaningful TPV acceleration.
🌐 Nebius Group NV (NASDAQ: NBIS) – AI-centric cloud platform built for intensive AI workloads. Sold Yandex to a consortium of Russian investors. Retains several businesses outside of Russia. 🇼🏷️
Note: Investing.com has a full calendar for most global stock exchanges BUT you may need an Investing.com account, then hit “Filter,” and select the countries you wish to see company earnings from. Otherwise, purple (below) are upcoming earnings for US listed international stocks (Finviz.com):
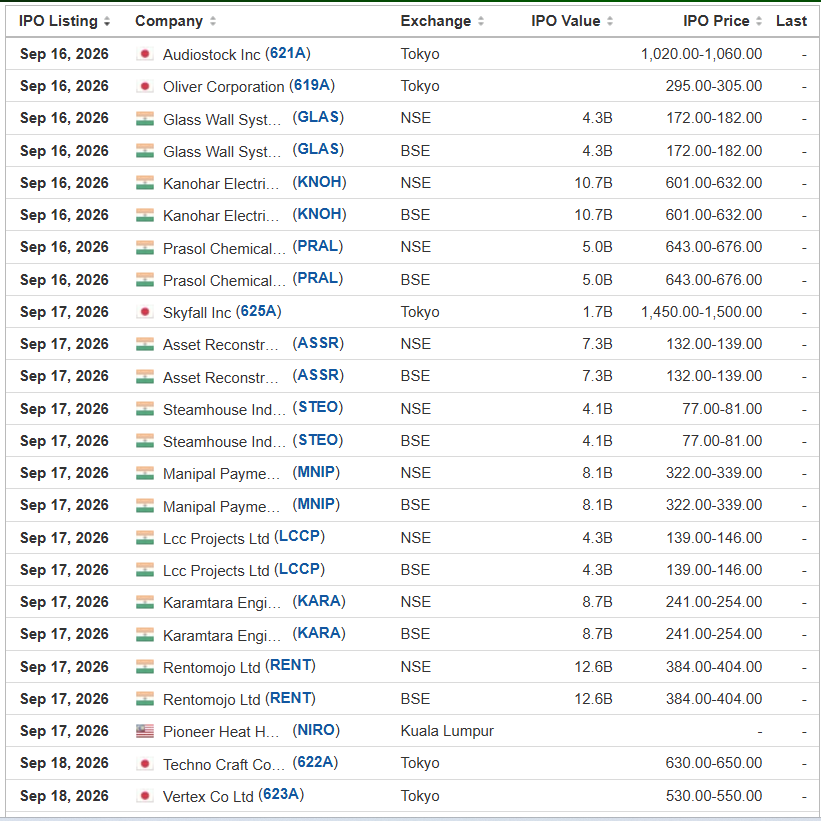
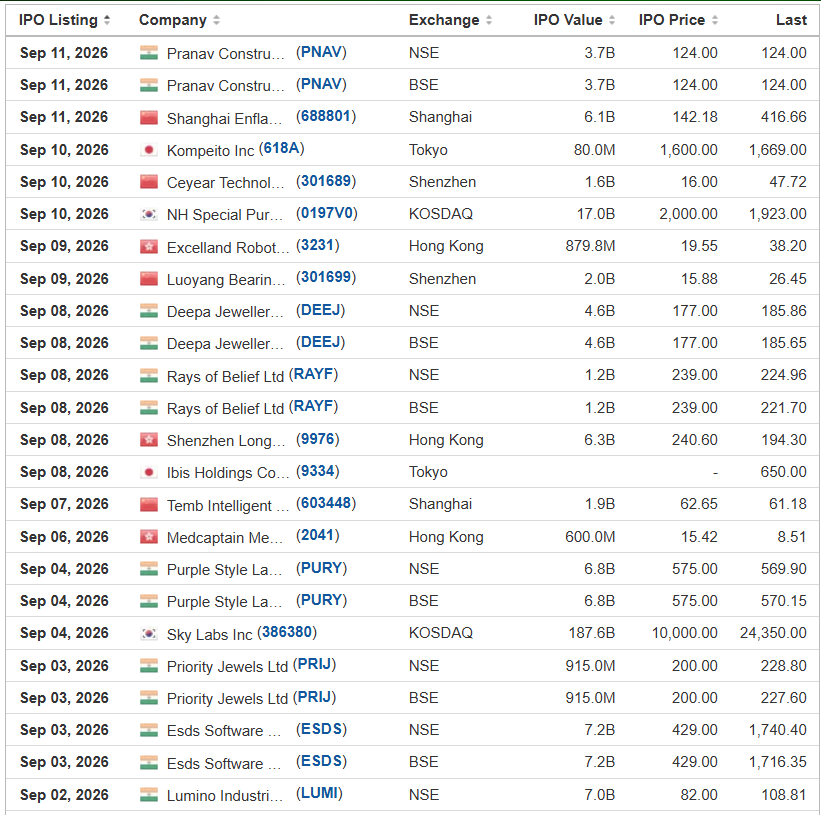
Frontier and emerging market highlights from IPOScoop.com and Investing.com (NOTE: For the latter, you need to go to Filter and “Select All” countries to see IPOs on non-USA exchanges):
Web3Labs Global Inc.MDAT Eddid Securities USA, 6.3M Shares, $4.00-5.00, $28.1 mil, 9/24/2026 Week of
(Incorporated in the Cayman Islands)
We are a Hong Kong-based company that provides Web3-related business services to support blockchain companies and decentralized tech enterprises, including start-ups.
We aim to create a Web3 entrepreneurial platform through diverse services, investment acceleration, and technical collaboration.
We are an innovative Hong Kong-based Web3 service provider dedicated to empowering enterprises including start-ups in the blockchain space through comprehensive, tailored support. Web3 ecosystem refers to industries focused on the decentralized evolution of the internet, powered by blockchain technology, enabling user-owned data, peer-to-peer transactions, and trustless systems without intermediaries. We seek to promote the adoption of and commercialization of decentralized solutions by facilitating a robust ecosystem of resources, expertise, and opportunities. Since our inception, we have supported many enterprises in Web3 including many start-ups with incubation, consultation and operational services, and are working to establish an active presence through regional hubs in Asia. By fostering innovation, collaboration, and compliance, we seek to serve as a catalyst for the growth of the blockchain industry in Asia, helping enterprises transform forward-thinking ideas into scalable realities.
Our comprehensive service offerings in the Web3 ecosystem primarily include (i) strategic consulting services (such as producing feasibility reports and consultation regarding business models in the Web3 industry), (ii) acceleration program management services, where we bridge early-stage companies to blockchain infrastructures, bolstering the companies’ development in their applications including decentralized solutions and their commercialization through token generation events and market integration, and (iii) general business services including marketing, market research and other business consulting services provided to third-party startup entities (such as market trend analysis and marketing strategy support, coordination of collaboration opportunities, which serve to facilitate such early-stage companies in accessing infrastructure, industry resources, and applicable policies). We provide companies with services from the formation of a start-up through later stages of corporate development, and we are dedicated to helping companies establish their presence in Hong Kong.
As of the date of this prospectus, we have established relationships with eight public blockchains (a decentralized and open network that allows anyone to participate, read, and write data without requiring permission from a central authority) and an affiliate of another public blockchain in the Web3 ecosystem, including Neo, Zetrix, Ton, Mango, and Plume.
In addition, we aim to create a dynamic ecosystem that connects enterprises, investors, and regulators through venues including policy forums (such as the co-hosted real-world assets (“RWA”) policy forum) and advisory reports, aiming to promote the integration of decentralized technologies with traditional industries. This vision drives our efforts to foster sustainable growth and global connectivity for Web3 enterprises.
In the face of global technological competition in the cryptocurrency ecosystem, we strive to stay at the forefront of the market and have a deep understanding of the needs and challenges of entrepreneurs in the Web3 ecosystem. We are dedicated to facilitating a legitimate, comprehensive, professional, and in-depth entrepreneurial environment in the Web3 economy.
Note: Net income and revenue are in U.S. dollars for the 12 months that ended Dec. 31, 2025.
(Note: Web3Labs Global Inc. filed its F-1 on May 13, 2026, for its IPO and disclosed the terms: 6.25 million shares at a price range of $4.00 to $5.00 to raise $28.13 million, if priced at the $4.50 mid-point of its range.)
Climate change and ESG are some recent flavours of the month for most new ETFs. Nevertheless, here are some new frontier and emerging market focused ETFs:
I have changed the front page of www.emergingmarketskeptic.com to mainly consist of links to other emerging market newspapers, investment firms, newsletters, blogs, podcasts and other helpful emerging market investing resources. The top menu includes links to other resources as well as a link to a general EM investing tips / advice feed e.g. links to specific and useful articles for EM investors.
Disclaimer. The information and views contained on this website and newsletter is provided for informational purposes only and does not constitute investment advice and/or a recommendation. Your use of any content is entirely at your own risk and it is your sole responsibility to evaluate the accuracy, completeness and usefulness of the content. Seek a duly licensed professional for any investment advice. I may have positions in the investments covered. This is not a recommendation to buy or sell any investment mentioned.
Emerging Market Links + The Week Ahead (September 14, 2026) was also published on our website under the Newsletter category.