Last week, the haze in Kuala Lumpur from Indonesia (that’s blanketing much of the region) seemed to be the worse in at least a decade (even my head was bothering me and I was forced to keep sliding glass doors mostly closed) with rain finally giving some relief this weekend.
What seems different this year unlike a decade ago is the lack of the usual finger pointing or blame game by the governments of Singapore/Malaysia (“Your peat is on fire!”) and Indonesia (“Its your listed companies doing the burning!”). Its like this has become acceptable (at least by governments) and like having dry/rainy seasons, we have a haze season.
The 🇮🇩 Indonesia, 🇲🇾 Malaysiaand🇸🇬 Singaporesections of ourSoutheast Asia Stock Indexlists a number of listed plantation companies; but they probably aren’t going to be impacted much since Malaysia and Singapore appear to have no political will to investigate their listed companies – many of which are state owned or have shares held by their provident funds (for the record, I think Malaysian plantation companies have been saying the fires are outside their plantations where there is little they can do about them).
On the other hand, I would imagine Genting Berhad(KLSE: GENTING / OTCMKTS: GEBHY), Genting Malaysia(KLSE: GENM OTCMKTS: GMALY / GMALF), Las Vegas Sands (NYSE: LVS), Singapore Airlines (SGX: C6L / FRA: SIA1 / OTCMKTS: SINGY / SINGF) and other hospitality or F&B related businesses (many eating places have outdoor or open to the outside seating under fans as we are in the tropics) are probably going to feel an impact. e.g. Haze season is roughly September to November while China’s Golden week is always around the beginning of October plus there were just Formula 1 weekends in both KL/SG, Diwali is coming and people always travel to/around Malaysia/Singapore on weekends or do staycations in nice local hotels.
But why would you stay at and go to the Marina Bay Sands’ infinity pool/observation deck if you won’t be able to see anything and will be choking on haze?
Little sunlight is also impacting locally grown produce; but, for example, lettuce from Australia costs double than lettuce grown in Malaysia:
However and on Friday night, I went to the Nine Emperor Gods festival in nearby Ampang and it was a huge crowd (despite the haze and earlier evening rain) with even more food than usual (I was the only westerner there). Of course, the air inside the temple complex and where the giant candles are burned outside was still much worse than the air over the city (I had to wash out my backpack, camera bag and clothes to get the incense etc smell out). So local life, at least in Malaysia, has gone on…
Otherwise, this post took a little longer as it covers a number of new research pieces – including two from Latam Stocks Substack with a number of new Brazilian stocks that I should add to the 🇧🇷 Brazil (184) section of our North & Latin America Stock Index.
$ = behind a paywall
$ = Behind a paywall / 🗃️ = Link to an archived article (Note: Seeking Alpha earnings/conference etc. presentations are typically not paywalled) / ⛔ = Article archiving may not be working properly
Korea seen as most vulnerable while Singapore and Hong Kong could transmit losses and funding stress as financial hubs
“But increasingly stretched valuations, rising leverage, and investment concentration have heightened the risk of a disorderly market correction,” warns the Asean+3 Macroeconomic Research Office (Amro).
Moreover, the Asean+3 economies ( including China, Japan and South Korea ) are particularly exposed because the region sits at the centre of the global AI supply chain, which means it is increasingly integrated into AI-related financial markets.
At ¥899 a share, Ai Robotics Inc (TYO: 247A / FRA: 85A) is worth ¥58.5bn, or about $370m. It sells skincare, hair dryers and salon products, and its sales have doubled four years in a row.
Ai Robotics sells beauty products made by contract manufacturers. The name comes from its own software, SELL, which it says uses AI and automation to plan products, buy online ads and forecast demand. Its skincare brand Yunth is best known for a pure vitamin C serum in single-dose capsules. Under the Brighte brand it sells hair dryers and face devices, and under Straine it sells shampoo. In April the company bought BJC, which sells eyelash serum and cosmetics through about 40,000 beauty salons.
Larger volumes of ECM and DCM transactions drive fee pool
According to LSEG figures, underwriting fees from equity capital market ( ECM ) deals amounted to US$3 billion, accounting for 23.3% of China’s investment banking fee pool and representing a 40% increase compared with the first three quarters of 2025.
By sector, high-technology led Chinese ECM activity in the first three quarters of 2026 with US$62 billion, accounting for 38.9% of the proceeds, making it the highest first three-quarter total since 2023. Changxin Memory Technologies (CXMT) (SHA: 688825) was the biggest IPO so far this year, with proceeds of US$9.84 billion equivalent, according to LSEG. Other high-technology Chinese IPOs during the period included HKC Corporation (SHE: 001399) ( US$1.25 billion ), CanSemi Technology Inc (SHE: 301660) ( US$1.06 billion ) and Shanghai Enflame Technology Co Ltd (SHA: 688801)’s Tencent (HKG: 0700 / LON: 0LEA / FRA: NNND / SGX: HTCD / OTCMKTS: TCEHY) ( US$910.57 million ).
The probe, announced on Friday, covers vertical power delivery systems, their components and computer systems containing them. Such systems deliver electricity to high-performance chips, including CPUs, GPUs and custom processors, where rising power demands must be managed in tight spaces and under thermal and voltage constraints.
Asia Cement (China) Holdings Corp (HKG: 0743 / FRA: 4OJ / OTCMKTS: AMNTF) is a Hong Kong-listed cement producer with operations in mainland China. It is controlled by Taiwan’s Asia Cement Corp (TPE: 1102). In a sector plagued by overcapacity and weak demand from the property market, the company stands out for one striking feature: a massive cash and deposit position that significantly exceeds its entire market capitalization. The shares trade at a deep discount to both book value and net cash, reflecting the market’s skepticism about the Chinese cement industry’s near-term prospects.
Asia Cement (China) manufactures and sells cement, clinker and related products, primarily serving construction and infrastructure markets in China. Like most Chinese cement producers, it has faced prolonged pressure from slowing property development, excess industry capacity and soft pricing. Revenue in 2025 was approximately RMB 5.1 billion, down from prior years, with profitability remaining thin or intermittently negative depending on the period. The company maintains production assets, quarries and a relatively conservative operating footprint compared with some larger peers.
I’ve been looking through some new Alibaba (NYSE: BABA) notes/research from Citi and Nomura this week and wanted to share my thoughts on their estimates and how they compare with what I’m expecting.
I’m still bullish, obviously. Roughly 50% cloud growth is the assumption I’m working with for the September quarter, and I’m hoping to see cloud EBITA margins continue trending higher after we finally got a meaningful increase last quarter.
I also continue to think quick-commerce losses can narrow fairly quickly from here, helping e-commerce profitability recover. Some of the earnings revisions below point in that direction, though there’s still plenty Alibaba needs to deliver on.
The observation that PDD Holdings (NASDAQ: PDD) orPinduoduo’s market share grew rapidly and then stalled at 19—24% against Alibaba (NYSE: BABA) is a hint that perhaps PDD business model is not what it seems at first glance.
On the surface, PDD looks like a horizontal retailer, the online-only platform lists an enormous catalog with millions of SKUs.
However, if PDD was really a horizontal model, then how did it succeed against the well-established Alibaba?
Actually PDD is a vertical retailer disguised like a horizontal.
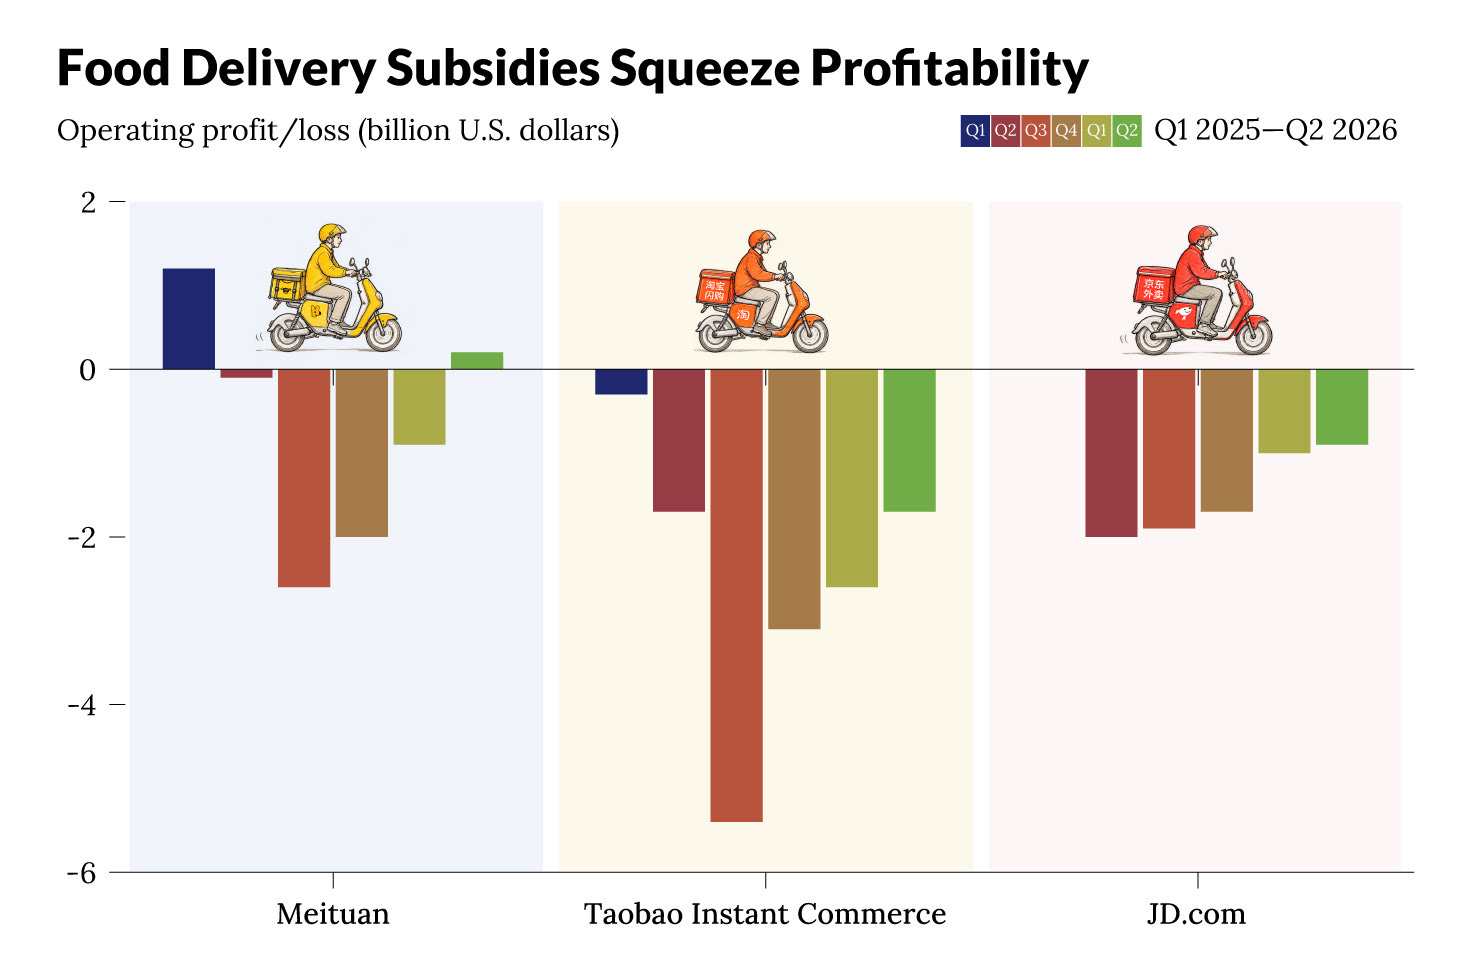
Li Ling still looks back on the summer of 2025 with a mix of nostalgia and disbelief. When China’s e-commerce giants waged an unprecedented food delivery subsidy war, her milk tea shop was overwhelmed by orders placed through JD.com(NASDAQ: JD / SGX: HJDD). The store’s pudding sago drink, priced at 11 yuan ($1.60), cost consumers just 1 yuan after a hefty platform discount.
But the bonanza did not last. By the fourth quarter, platform subsidies had dried up, replaced by growing pressure on merchants to shoulder promotional costs. What began as an aggressive land grab by industry heavyweights, which spent more than 150 billion yuan to capture market share, ultimately squeezed merchants’ profits and pushed platforms themselves into losses.
Market leader Meituan (HKG: 3690 / 83690 / SGX: HMTD / FRA: 9MD / OTCMKTS: MPNGF / MPNGY) swung to a net loss of about 23.4 billion yuan in 2025, while rivals JD.com Inc. and Alibaba (NYSE: BABA)’s Taobao Instant Commerce racked up steep operating losses in food delivery.
Runs WeChat, China’s super app, with about 1.44 billion monthly users
The world’s largest video game publisher by revenue
I work close enough to AI to believe it will change everything. But I also know how hard it is to guess where the money will end up. The best model changes every few months. Plenty of products that look magical in a demo never become a habit. And a tool can be very useful and still make more money for the people using it than for the company selling it.
So when it comes to investing, the question I ask is: where is AI already showing up in the revenue a company reports today?
USD and Dim Sum deals secure tighter pricing due to strong investor demand
Chinese technology and entertainment conglomerate Tencent (HKG: 0700 / LON: 0LEA / FRA: NNND / SGX: HTCD / OTCMKTS: TCEHY) returned to the offshore bond market in another major fundraising exercise, pricing on October 13 a dual-currency, multi-tranche offering amounting to US$5.7 billion equivalent.
The deals included a US dollar offering in two tranches: a 10-year bond amounting to US$1.3 billion and priced at a spread of 90bp over the US treasuries and a 20-year bond amounting to US$500 million with a spread of 115bp over the US treasuries. Both final pricing represented a 25bp tightening from their initial price guidance of 115bp area and 140bp area, respectively.
The company, formerly known as Inke, was China’s second largest livestreaming platform in 2017 before launching apps for social networking, dating and micro-dramas
Inkeverse Group Ltd (HKG: 3700 / FRA: 5IK)is dropping its micro-drama business after just four years in the face of overwhelming competition from AI-generated content
The sale of its Kuaichuang Network unit will cost Inkeverse nearly a quarter of its revenue, but frees up cash for its data center business plans
Shares of Guangzhou CanSemi Technology Inc. [CanSemi Technology Inc (SHE: 301660)] more than tripled in their trading debut on the Shenzhen Stock Exchange as investors piled into the Chinese mainland’s sole large-scale producer of 12-inch silicon photonics wafers.
The strong market reception highlights robust investor appetite for domestic semiconductor manufacturers poised to capitalize on the AI boom, despite the analog chipmaker’s massive ongoing losses.
The recent 5-week continuous decline has pushed prices into statistical outlier territory, triggering a very high probability of a mean-reversion bottom within 1–2 weeks, according to our model.
Solid index backing and upcoming Q3 earnings (Oct 31) support a high-conviction LONG asymmetric risk entry targeting a medium-term bounce to HKD 70–80 (a conservative target versus consensus).
Shenzhen Transsion Holdings (SHA: 688036 / HKG: 2636), a mobile phone maker focused on Africa and other emerging markets, raised HKD 2,968.0m (USD 378.2m) and will list on HKEX on Thursday, 15 Oct 2026.
In our previous notes, we looked at the company’s fundamentals and the deal terms.
In this note, we provide an update for the IPO before its trading debut.
Tuya Inc (NYSE: TUYA) is probably the most important smart-home company most people have never heard of. If you have bought a cheap smart plug, a Lidl Silvercrest sensor or a no-name Wi-Fi bulb from Amazon and controlled it through the “Smart Life” app, there is a good chance it ran on Tuya. The company is the invisible operating system behind hundreds of thousands of connected products from thousands of brands.
What made me look twice is the balance sheet. At about $1.69 per share, Tuya has a market cap of roughly $1.04 billion. Almost $976 million of that is cash, time deposits and treasury bills. The company is profitable on a GAAP basis, pays a dividend, has no meaningful debt, and grew revenue by 16% last quarter.
Strip out the cash and you are paying almost nothing for a global market leader in IoT platforms.
The company plans to buy a garden equipment maker for a bargain price, aiming to expand its own lawnmower sales by leveraging the German company’s channels
Shenzhen Ldrobot Co Ltd (HKG: 1236) plans to acquire Germany’s Sabo for up to 6 million euros, aiming to tap the company for its brand, and distribution and service networks
A growing focus on smart lawnmowers is driving a structural change in LDRobot’s revenue mix, but brand building and product development expenses are rising
China’s domestic passenger car retail sales tumbled 28% year-on-year in September to 1.62 million vehicles, marking the steepest monthly decline of the year as the industry’s traditional peak season failed to materialize.
The sharp decline underscores entrenched consumer caution that aggressive price discounting and a steady stream of new model launches have failed to reverse. While surging vehicle exports continue to cushion overall production, foreign shipments have not fully compensated for cooling demand at home.
Xiaomi (HKG: 1810 / SGX: HXXD / FRA: 3CP / OTCMKTS: XIACF)smartphone ASP grew 25% QoQ thanks to the premiumization strategy, which helps to cover the bleeding from the EV unit.
The ASP hike unfortunately won’t be enough to cover the ongoing loss from the EV unit, even from the dual-screen new units.
With the launch of Beijing Phase II and SkyNomad SUV series, Xiaomi may be able to sell more than 40,000 units/month, which adds back RMB 2.6 billion.
China Beststudy Education Group (HKG: 3978) operates in China’s private education market and provides talent education, tutoring programs and test preparation services mainly to school-age children from primary school through secondary school.
After the Chinese government’s severe crackdown on private education in 2021, China Beststudy Education has been able to remarkably stage a turnaround, especially focusing on the talent education market.
The company has high dividend yield (more than 10%) with attractive valuations (EV/EBITDA of 1.3x and P/E of 5x).
Over the past few months I built a thesis on MINISO Group Holding (NYSE: MNSO)MNSO -1.64%↓ around one simple idea. The relevant question was no longer whether the company could grow. It was whether it could turn that growth into something harder to achieve: real operating leverage.
I wrote that thesis after reviewing several consecutive quarters in which revenue advanced strongly but adjusted profit fell short of that acceleration. My conviction rested on four pillars that I considered already underway:
Membership as a repurchase engine in China;
The maturation of large-format store cohorts in international markets;
Explosive, sustained international growth, faster than China’s, since the US is the largest market in the world; and
The development of proprietary intellectual property (IP), with YOYO as the flagship case.
The Q2 2026 report did not destroy that thesis. But it forced me to do something I should do more often as an analyst: separate what the evidence confirms from what I simply hoped would happen.
In this post I want to show where I was right, where I was prematurely optimistic, and what I need to watch before I feel comfortable with my own assumptions again.
The cement and concrete arm of the China Resources group has flagged up a deepening loss, hit by falling prices for its products and rising manufacturing costs
Visa has received preliminary approval from the People’s Bank of China (PBOC) to establish a bank card clearing institution, paving the way for the U.S. payments giant to support the issuance of yuan-denominated Visa cards and provide domestic card clearing services.
Visa Information Technology (Beijing) Co. Ltd., Visa’s China entity, has one year to complete preparations before applying to begin operations, according to a PBOC statement released Tuesday.
A cancer drug developed by the Chinese firm has entered the European regulatory process and Novo Nordisk has bought rights to a potential weight-loss therapy
Syngenta, the Sinochem-controlled crop protection and seeds group, has reportedly filed confidentially for a Hong Kong listing of about USD5bn. Bookrunners include CICC, UBS, BOA, GS and CITIC.
We review Syngenta’s withdrawn Shanghai application and its financials, including losses, debt and goodwill.
We also look at the industry cycle through its three A-share subsidiaries, and at corporate governance issues, including an anonymous complaint to HKEX.
Dynamic Electronics, a printed circuit board (PCB) makerfocused on automotive electronics, is seeking an A+H listing. CICC and Guolian are the joint sponsors.
We look at the company’s core segments: automotive electronics, data storage, and communications and AI servers.
We discuss our preliminary thoughts on the company’s valuation based on the A-H premium.
Amlogic, a fabless designer of processors for set-top boxes, smart TVs and smart devices, is seeking an A+H listing. CICC and Haitong are the joint sponsors.
We look at the company’s core segments: smart multimedia and display SoCs, and AIoT SoCs.
We discuss our preliminary thoughts on the company’s valuation based on the A-H premium.
The SFC [Securities & Futures Commission of Hong Kong] acted against both IPO issuers and investors, suspending Cloudbreak and Baicha and making the largest asset restriction in SFC history.
The SFC suspects syndicates created false demand for IPO shares, and IPO proceeds may have returned to them through undisclosed financial-product agreements.
Based on the SFC press releases, we summarize red flags usable in ECM research and investment, three before listing and two after listing.
Hong Kong’s securities regulator froze nearly HK$4.7 billion ($599 million) in assets and ordered a trading halt in bubble-tea chain ChaPanda [Sichuan Baicha Baidao Industrial (HKG: 2555)] in a crackdown on suspected initial public offering manipulation.
The action targets two syndicates suspected of using illicit guaranteed-allocation schemes to inflate apparent demand for new listings. It includes the Securities and Futures Commission’s (SFC) largest asset freeze in a manipulation case to date.
Hong Kong’s Securities and Futures Commission (SFC) plans to expand its oversight powers to curb listing misconduct and address emerging risks.
The regulator published consultation conclusions Monday on amendments to the Securities and Futures (Stock Market Listing) Rules, with the changes expected to take effect in the first quarter of next year, subject to the legislative process.
Constituents increase from 30 to 50, incorporating more AI and advanced hardware companies
The Hang Seng Tech Index ( HSTECH ), Hong Kong’s flagship benchmark tracking technology-related stocks, will refine its stock selection process and broaden market coverage to enhance investability, index operator Hang Seng Indexes Co Ltd ( HSIL ) announced on October 7.
In its most prominent methodology revamp since it launched in 2020, HSTECH will undergo six key changes, effective December 7. It will remove the sector requirements; increase technology themes from five to six; expand technology sub-themes from 16 to 24; define the eligible universe as constituents of the Hang Seng Composite LargeCap & MidCap Index ( HSLMI ); introduce a two-stream constituent-selection mechanism that considers both market and sales growth; and broaden constituents from 30 to 50. The 8% single-stock weight cap and the quarterly review cycle stay unchanged.
Brokerage CLSA Ltd expects the Macau gaming sector’s third-quarter reported earnings before interest, taxation, depreciation and amortisation (EBITDA) to have fallen 11 percent year-on-year, to just under US$1.84 billion.
Analyst Jeffrey Kiang stated in a Monday note that such decrease was “amid a 3.8 percent year-on-year decline” in the sector’s third-quarter gross gaming revenue (GGR) to MOP60.21 billion (US$7.45 billion)
Though he stated: “Headwinds on margins should be mitigated by above-normal VIP win rates in the quarter, which we see as temporary support.”
The Macau government collected just over MOP74.56 billion (US$9.22 billion) in fiscal revenue from gaming in the first nine months of 2026, according to the latest data released by the city’s Financial Services Bureau. The figure was up 5.9 percent from the prior-year period.
Macau’s casino gross gaming revenue (GGR) averaged approximately MOP729 million (US$90.2 million) a day from October 5 to October 11, despite recent softness in high-end play, suggested banking institution UBS, citing its own channel checks.
Macau’s third-quarter gross gaming revenue (GGR) in the mass-market casino gambling segment – including slot machine play – stood at nearly MOP43.31 billion (US$5.36 billion), down 5.2 percent on the prior-year period.
Mass play was 71.9 percent of all casino GGR for the quarter, versus 73.0 percent in third-quarter 2025.
Seaport Research Partners expects earnings before interest, taxation, depreciation and amortisation (EBITDA) for the city’s casino industry to have fallen by 10.6 percent year-on-year in the third quarter.
Senior analyst Vitaly Umansky said in a memo issued on Monday that the industry-wide EBITDA margin for the July to September 2026 period would in likelihood show a year-on-year decline of nearly 180 basis points, although it was potentially up by 50 basis points quarter-on-quarter.
Casino operators Wynn Resorts Ltd (NASDAQ: WYNN) and Melco Resorts & Entertainment Ltd (NASDAQ: MLCO) have several potential catalysts to support future business growth, including new hotel investments in Macau, and the expansion of entertainment offerings and opportunities in international markets, according to brokerage Texas Capital Securities.
In a Monday report, analyst David Bain said that despite recent weakness in Macau’s gross gaming revenue (GGR), Wynn Resorts – parent of Wynn Macau Ltd (HKG: 1128 / FRA: 8WY / OTCMKTS: WYNMY / WYNMF) – continued to regard the market as “very solid”, with “strong investment potential”.
The brokerage highlighted the Wynn group’s planned Enclave hotel tower development at Wynn Palace, as well as a theatre project, as examples of investments that could support the operator’s future performance in Macau.
Outside Macau, Texas Capital highlighted the potential contribution from Wynn Al Marjan Island, the group’s casino resort project in Ras Al Khaimah, a member of the United Arab Emirates (UAE).
The South Korean casino sector could see an outflow of as much as KRW2.32 trillion (US$1.72-billion) in annual gaming spend, once the MGM Osaka integrated resort (IR) with casino launches in Japan in 2030.
That is the forecast of an academic study presented by Kyung Hee University tourism professor, Lee Chung-ki (pictured), at a Korea Casino Association forum on Wednesday. The session was titled: “Impact Analysis of Japan’s Introduction of Casino Integrated Resort (IR)”
The study suggested MGM Osaka could divert between KRW316.51 billion to nearly KRW1.27 trillion in gaming spend from Kangwon Land (KRX: 035250) – South Korea’s only casino resort offering gambling to locals. The country’s 17 foreigner-only casinos could lose between KRW807.07 billion to KRW1.05 trillion, according to the latest study.
The secretary-general of the Korea Casino Association (KCA) has told GGRAsia the body has yet to hear from the South Korean government on how it would implement an enlarged, up to 15 percent, levy on each casino’s revenue to support a tourism fund.
That is according to the KCA official, Shin Jong Ho (pictured), speaking on the sidelines of a Wednesday forum in Seoul, the country’s capital.
Mr Shin said the association had only been informed that the maximum contribution rate per casino towards the Tourism Promotion and Development Fund, could rise to 15 percent of annual revenue, from the current 10 percent.
S-1 Corp (KRX: 012750) announced outstanding shareholder return plans. The company plans to cancel all of its existing treasury shares (11% of its outstanding shares).
It also announced a tender offer of 450 billion won. Tender offer price is 99,000 won and the number of shares allotted is 4.545 million (12% of outstanding shares).
The combined share cancellation of existing treasury shares and the tender offer of additional shares should help to boost higher ROE, EPS, and higher share price.
Hanwha Systems Co Ltd (KRX: 272210) plans to sell a 7.24% stake in Hanwha Ocean (KRX: 042660) to raise about 1.38 trillion won ($1.0 billion) through a Price Return Swap (PRS) agreement.
This deal is likely to have a positive impact on Hanwha Systems and negative impact on Hanwha Ocean.
The transaction is PRS-based so that if Hanwha Ocean’s stock price falls below the base price at the settlement date one year from now, Hanwha Systems will pay the difference.
On 16 October, Hyundai Elevator Co Ltd (KRX: 017800 / OTCMKTS: HYEVF) announced it plans to sell about 5.8% stake in its subsidiary Hyundai Movex and also cancel 6.4% of Hyundai Elevator’s own treasury shares.
These measures are likely to accelerate Hyundai Elevator’s effort to improve corporate governance and increase shareholder returns.
Hyundai Elevator has a high expected dividend yield of 11.5% in 2026.
The leading candidate for the M&A of Joongang Ilbo is actually the DaouKiwoom Group/CJ Group.
All in all, I think it would be best for Daou Kiwoom Group/CJ Group to stick to their core businesses, rather than trying to acquire Joongang Ilbo newspaper.
It is time for the existing shareholders of Daou Kiwoom and CJ Group companies to voice their dissent against the acquisition of Joongang Ilbo.
Terton Capital and FCP have sent open letters to Orion Corp (KRX: 271560)’s board of directors, urging the company to abandon its M&A of Joongang Ilbo (leading Korean newspaper) and improve corporate governance.
Clearly, this potential acquisition of Joongang Ilbo by Orion Corp is likely to negatively impact Orion Corp mainly due to lack of synergies between the two businesses (food vs newspaper).
This is a near-textbook example of when corporate activists should step in to prevent a company (Orion Corp) in doing something foolish (excessive M&A in a non-core business – newspaper).
DTS finalized its IPO price at 18,500 won (high end of IPO price range). A total of 2,381 institutions participated in the demand forecasting. Demand ratio was 983.98 to 1.
Based on the finalized offering price, the total proceeds from the IPO amount to approximately 41.2 billion won, and the company’s expected market capitalization post-listing is around 275.3 billion won.
My base case valuation of DTS is a target price 29,360 won per share, which is 59% higher than the IPO price (18,500 won).
Substantial interest from new investors, strong confidence amid global economic instability
Trading value and volume at the Cambodia Securities Exchange (CSX)hit all-time highs in September as the exchange’s index jumped more than 20%, marking a surge of more than 150% in the year to date.
Average daily trading value was 5.8 billion riel ( US$1.45 million ) – up almost two-thirds from the previous record of 3.6 billion riel in April 2022. Trading volume averaged 7.5 million shares a day.
Noting “substantial interest from new investors”, CSX says the number of new trading accounts opened in September was a record 4,162, surpassing the previous all-time high of 4,034 in September 2018. The number of active investors reached a record 9,806.
The CSX Index ended the month at 650.62 points, up 20.3% from August and 154% since the beginning of the year.
Malaysia’s Genting Berhad(KLSE: GENTING / OTCMKTS: GEBHY) will in likelihood need to “sell non-core assets” to stave off further credit-rating downgrades, despite a proposed MYR1.25-billion (US$305.8-million) rights issue, says CreditSights. The institution views the rights issuance as positive but thinks it will have only “modest impact” on the group’s credit metrics.
The credit research provider highlighted possible disposal of unused land parcels in Miami, in the United States, as a potential source of funds to reduce debt. It also expects Genting Bhd to avoid further debt-funded attempts to acquire shares in subsidiary Genting Malaysia Bhd over the next 12 to 18 months.
“We believe non-core asset sales will be the main tool to stave off downgrade risks, notably the unused Miami land parcels,” wrote analysts Jonathan Tan, Jun Jie, and Lakshmanan R in a Monday report.
Singapore recorded 1.23 million international visitor arrivals in September, down 2.2 percent year-on-year. The latest tally took the city-state’s aggregate visitor arrivals for the first nine months of this year, to 12.65 million, a decline of 1.7 percent year-on-year.
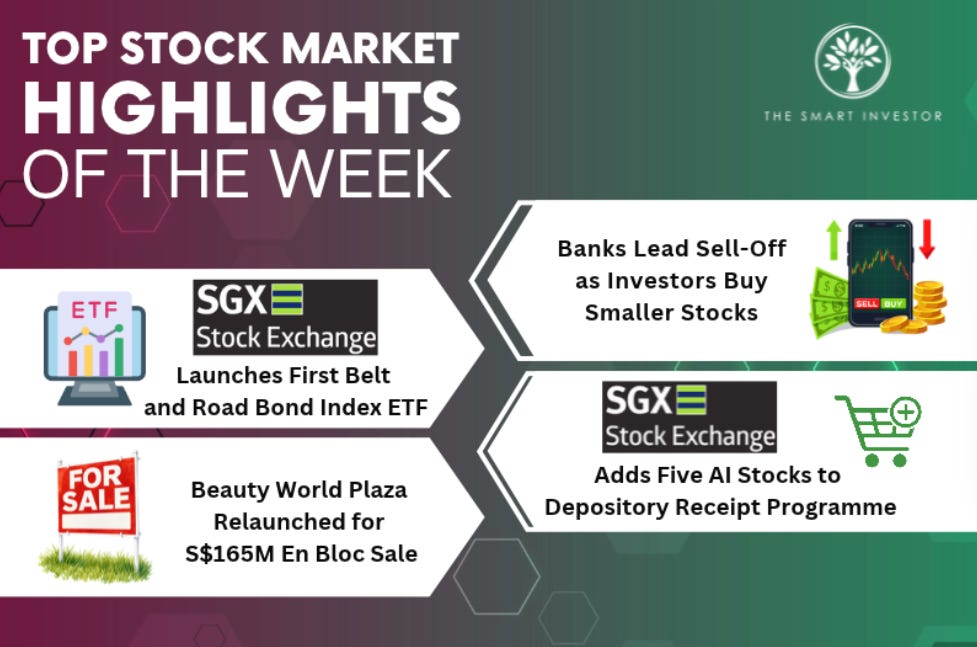
We look at where institutional money went as banks led a sell-off, two new SGX product launches, and a Bukit Timah property back on the en bloc market.
Smaller Counters Attract Institutional Buyers as Banks Lead the Sell-Off
Smaller board lots don’t make stocks cheaper. But they could change the way you build your portfolio.
When I first started buying Singapore stocks in 2012, one thing shocked me.
You needed a lot of money just to get started.
Back then, a standard SGX board lot was 1,000 shares.
DBS Group (SGX: D05 / FRA: DEVL / DEV / OTCMKTS: DBSDY / DBSDF) traded at an average of about S$13.98 in 2012. That meant buying just one lot could cost nearly S$14,000.
When the board lot decides your portfolio for you
From 1,000 shares to 100, and now 10
A good company can still be too big a position
You do not have to make one big decision
One catch: trading costs still matter
Get Smart: Start small, think about the whole portfolio
Oversea-Chinese Banking Corp (OCBC) (SGX: O39 / FRA: OCBA / FRA: OCBB / OTCMKTS: OVCHY) has been a popular choice among Singapore dividend investors, but how much income would a S$20,000 investment made ten years ago have generated?
How We Calculate the 10-Year OCBC Investment
What Was OCBC’s Dividend Like 10 Years Ago?
Back in 2016, OCBC paid a final dividend of S$0.36 per share, yielding roughly 4.1% given a purchase price of S$8.69.
Today’s annualised yield is lower at 3.2%, because the share price has risen faster than the dividend.
The dividend growth path wasn’t straight, though.
How Much Would the S$20,000 Investment Have Generated in Dividends?
What Would the Investment Be Worth Today?
What If You Reinvested Every Dividend?
Your Yield on Cost Would Look Very Different
What Drove OCBC’s Dividend Growth?
Could OCBC Deliver Similar Dividend Income Over the Next 10 Years?
Get Smart: The Power of Holding a Quality Dividend Stock
Three cash-rich SGX stocks raised dividends in 1H2026, but only one generated more free cash flow, raising questions about payout sustainability.
Is Info-Tech’s dividend increase backed by cash?
Info-Tech Systems (SGX: ITS) sells cloud-based software for human resource management, accounting and customer relationship management, and runs AI training through Info-Tech Academy.
For 1H2026, revenue rose 22% year on year (YoY) to S$27.3 million.
Why did China Sunsine double its dividend while free cash flow fell?
Revenue for 1H2026 rose 19% YoY to RMB 2 billion as its average selling price and sales volume each climbed 9%.
Can Delfi keep raising its dividend as margins shrink?
Delfi Limited (SGX: P34 / OTCMKTS: PEFDF) is best known for its SilverQueen, Ceres and Delfi chocolate brands in Indonesia, and sells consumer products across 17 markets.
Revenue for 1H2026 rose 2.7% YoY to US$266.6 million.
Keppel DC REIT and CapitaLand Integrated Commercial Trust offer investors exposure to very different property sectors, but which REIT is the better buy?
Keppel DC REIT (SGX: AJBU / OTCMKTS: KPDCF), or KDCREIT, offers exposure to secular technology trends (AI and cloud computing) through its various data centres.
Singaporeans are expected to spend S$1.05 billion more in JB each year once the RTS opens. Here’s how FCT is responding.
The cross-border rail line is set to open in early 2027, and suburban mall owners have reason to pay attention.
A study commissioned by the Singapore Business Federation, the Restaurant Association of Singapore and the Singapore Retailers Association expects Singapore residents to spend S$1.05 billion more in JB each year once the RTS opens.
JB visitors, for their part, are expected to spend S$756 million more in Singapore.
Net it out, and around S$290 million a year flows out of Singapore.
How would you invest S$40,000 in Singapore blue chips? These four stocks stand out for their dividends, growth prospects and strong business fundamentals.
CapitaLand Integrated Commercial Trust, or CICT, is a retail and commercial real estate investment trust (REIT) with a resilient portfolio of properties across Singapore, Australia, and Germany.
As the operator of Singapore’s stock exchange, Singapore Exchange Limited, or SGX, provides the essential multi-asset infrastructure for trading equities, fixed income, currencies, and derivatives.
Singapore Technologies Engineering, or STE, is a global technology and engineering group specialising in aerospace, smart city, defence, and public security solutions.
Three iEdge Singapore Next 50 stocks spent S$27.1 million on share buybacks in 9M2026, but free cash flow reveals whether the repurchases are sustainable.
If you invested S$10,000 in iFAST Corporation Limited (SGX: AIY / FRA: 1O3 / OTCMKTS: IFSTF) 10 years ago, your investment could be worth around S$100,000 today. Here’s what drove its remarkable growth.
iFAST’s Humble Beginnings
iFAST was known for its Singapore-centric portal, distributing unit trusts through brands like Fundsupermart in 2000 and FSMOne in 2016.
Fast forward ten years to today (late 2026), iFAST is now a global digital banking and wealth management platform.
The S$100,000 Reveal: Cash Dividends vs Reinvestment
It is perhaps one of history’s most unlikely industrial success stories. India was desperately poor – a largely agricultural nation with weak infrastructure running a heavily regulated socialist economic model. Yet somehow, a number of billion dollar Indian tech giants managed to emerge. And through them, India became a monster IT service export powerhouse. Offshoring continues to strike strong emotions today. In today’s video, we look at the rise of the Indian IT export industry.
HDFC Bank (NYSE: HDB) is scheduled to report its Q2 FY27 earnings on Saturday, October 17.
Sashidhar Jagdishan term ends on October 26, 2026 and will be replaced by Anup Bagchi (from ICICI Group), this executive transition is a “clean slate” strategic reset.
The stock has lost 28% of its value since December 2025, but the last few weeks did show some bottoming process, our model says the stock may rise higher.
Jio Platforms, a digital connectivity provider, has filed its draft prospectus. Its 19 bookrunners include international banks MS, UBS, BOA, Citi, CLSA, GS, HSBC, Jefferies, JPM and BNP Paribas.
Our previous note included the company’s business, financials and pre-IPO investor backing.
In this note, we compare the company with its listed peers, forecast earnings and provide our thoughts on valuation.
Nearly 39% of Jio Platforms’s outstanding borrowings could be repaid, yet the estimated annualised earnings uplift remains below 7% of FY26 PAT.
Deferred payment and lease liabilities total approximately ₹1.18 lakh crore, highlighting the financing commitments that remain after the proposed repayment.
Sustained deleveraging will depend on capital expenditure discipline, customer monetisation and cash generation after contractual obligations.
Jio Platforms is launching India’s largest-ever IPO, raising up to Rs 30,213 crore entirely through a fresh issuance of equity to deleverage its balance sheet.
It marks a structural transition for Indian telecom from heavy capital expenditure and customer acquisition to high-margin cash generation, backed by a 53.3% EBITDA margin and over 533 million subscribers.
It redefines Jio from a pure-play telecom utility into an entrenched technology ecosystem and high-conversion free-cash-flow growth play.
We own around 1.5% of Georgia Capital Plc (LON: CGEO / FRA: 2IX / OTCMKTS: GRGCF). Buybacks have helped that stake grow without us having to buy all the additional shares ourselves.
Georgia Capital is currently around 3% of our portfolio.
Georgia Capital describes itself as a platform for buying, building and developing businesses in Georgia. The idea is to build businesses until they can operate independently and then sell them when somebody else is willing to pay an attractive price. The normal investment horizon is five to ten years.
Today, almost half the portfolio consists of one listed company:Lion Finance Group PLC (LON: BGEO / FRA: GEB / OTCMKTS: BDGSF), formerly Bank of Georgia Group. At the end of June, Lion Finance represented 47% of Georgia Capital’s portfolio value. The large private businesses accounted for another 43%, principally retail pharmacies; hospitals, clinics and diagnostics; and insurance. The remaining 10% includes businesses such as education, renewable energy, wine, hospitality and auto services.
Karl Miller’s new assessment: a seven-to-ten-year rebuild, a trillion-dollar bill, and a diesel crisis that Saudi Arabia can no longer cushion
For most of this war, Saudi Arabia has been the shock absorber of the world oil market. When Hormuz closed, Riyadh pushed crude west through the East-West pipeline to Yanbu on the Red Sea and kept at least part of its exports moving. That bypass is now under attack. Ansar Allah has seized islands at the mouth of the Red Sea, declared a “maritime ban” on Saudi shipping and claimed strikes on Saudi airports, and in September drones knocked the East-West pipeline largely out of service. Riyadh blamed that strike on Iranian-backed militias in Iraq. On October 4 a pumping station at Khurais, east of Riyadh, was hit for the first time and the pipeline stopped again.
Karl Miller, whose earlier assessment of the global fuel emergency I have drawn on before, has just completed a new analysis of what this means for Saudi Arabia and for the world. His conclusion is stark: the Gulf’s energy system will take far longer and cost far more to rebuild than anyone in Washington is admitting, and Saudi Arabia can no longer be counted on to cover the gap. Here are his key findings.
Both candidates did ok while the viewers and moderators suffered through it.
I watched most of the Brazilian presidential debate last night, as the two candidates stalked each other around the stage and Flavio stood behind Lula every time the president spoke. Here are a few notes going into the final week of the campaign.
74 offerings, R$110 billion raised—and a generation of Brazilian companies worth revisiting.
The aim of this series is to provide a very brief overview of each company, as well as its stock performance since the IPO. I want to put these names back on your radar so you can identify which deserve a closer look based on your investment criteria.
Lavvi develops apartments in São Paulo, mainly in the middle and upper ends of the market. It was formed in 2016 through a partnership involving Cyrela (CYRE3), which remains a shareholder; Lavvi has its own separate listing.
Méliuz began as a cashback and shopping platform, expanded into financial services, and subsequently changed direction again. Its major recent shift was adopting a Bitcoin treasury strategy in 2025, alongside the continuing shopping business.
Quero-Quero sells building materials, home-improvement products and household goods, mainly in southern Brazil, and provides consumer credit through VerdeCard.
🌐 Nebius Group NV (NASDAQ: NBIS) – AI-centric cloud platform built for intensive AI workloads. Sold Yandex to a consortium of Russian investors. Retains several businesses outside of Russia. 🇼🏷️
Microsoft and Meta prepaid the build. The stock is 45% off the high. The question is whether the backlog survives
Nebius[Nebius Group NV (NASDAQ: NBIS)] is what is left of Yandex after the carve-out. It is now a pure-play AI cloud that sells dedicated GPU capacity to the companies that cannot wait for their own data centers.
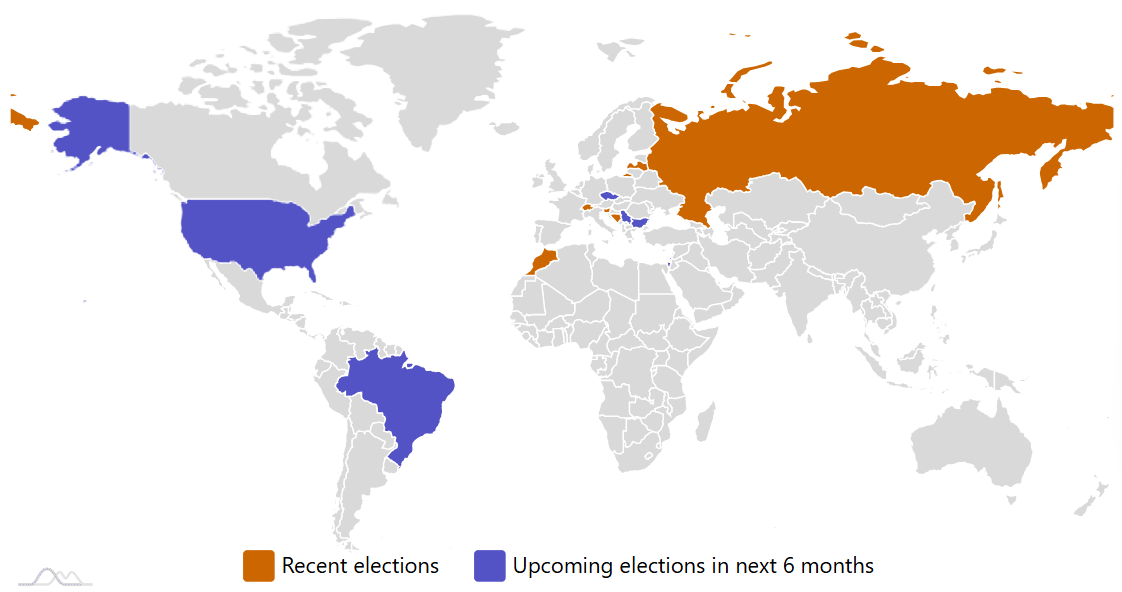
Note: Investing.com has a full calendar for most global stock exchanges BUT you may need an Investing.com account, then hit “Filter,” and select the countries you wish to see company earnings from. Otherwise, purple (below) are upcoming earnings for US listed international stocks (Finviz.com):
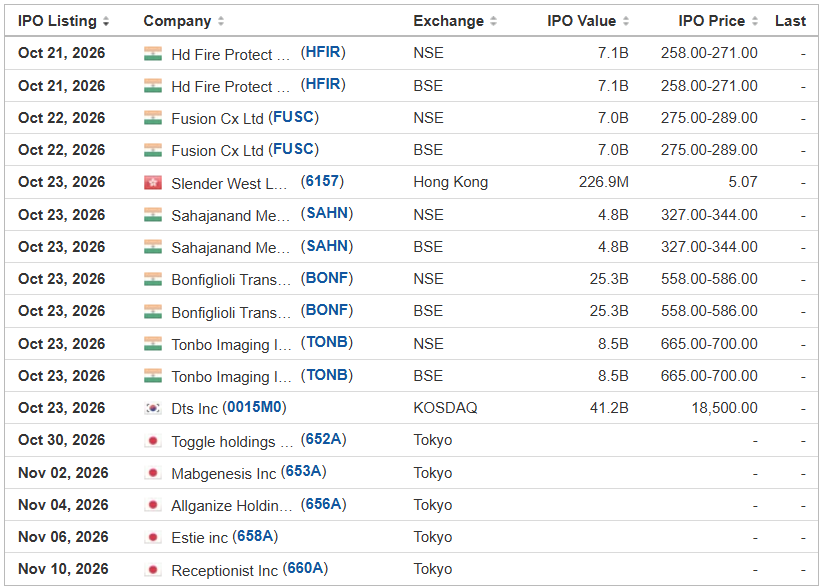
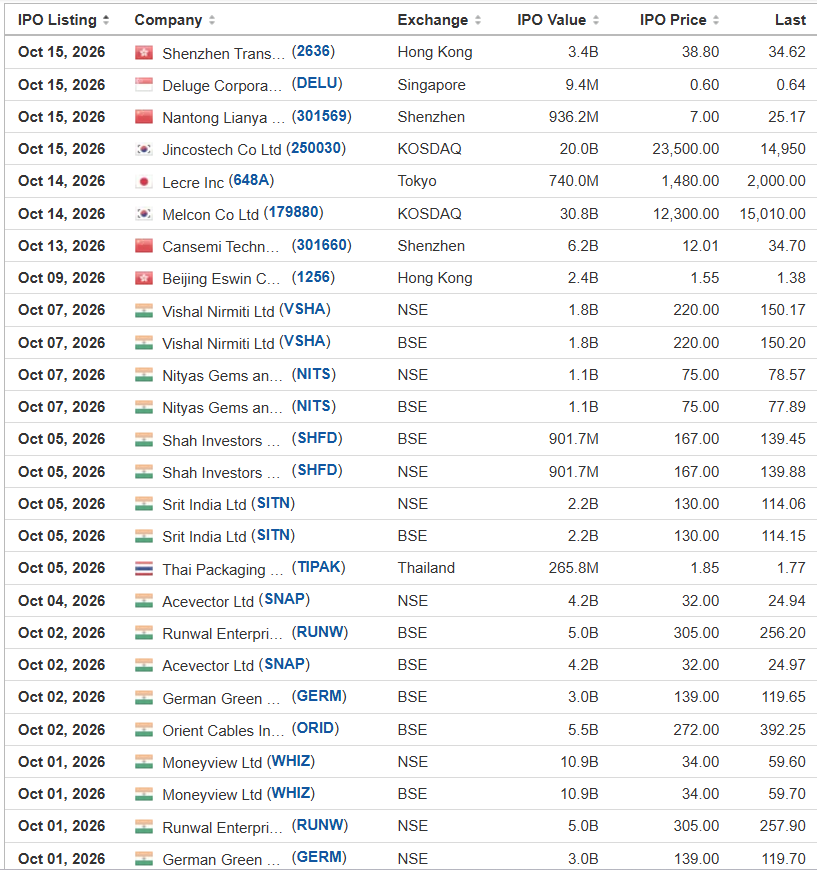
Frontier and emerging market highlights from IPOScoop.com and Investing.com (NOTE: For the latter, you need to go to Filter and “Select All” countries to see IPOs on non-USA exchanges):
Climate change and ESG are some recent flavours of the month for most new ETFs. Nevertheless, here are some new frontier and emerging market focused ETFs:
I have changed the front page of www.emergingmarketskeptic.com to mainly consist of links to other emerging market newspapers, investment firms, newsletters, blogs, podcasts and other helpful emerging market investing resources. The top menu includes links to other resources as well as a link to a general EM investing tips / advice feed e.g. links to specific and useful articles for EM investors.
Disclaimer. The information and views contained on this website and newsletter is provided for informational purposes only and does not constitute investment advice and/or a recommendation. Your use of any content is entirely at your own risk and it is your sole responsibility to evaluate the accuracy, completeness and usefulness of the content. Seek a duly licensed professional for any investment advice. I may have positions in the investments covered. This is not a recommendation to buy or sell any investment mentioned.
Emerging Market Links + The Week Ahead (October 19, 2026) was also published on our website under the Newsletter category.